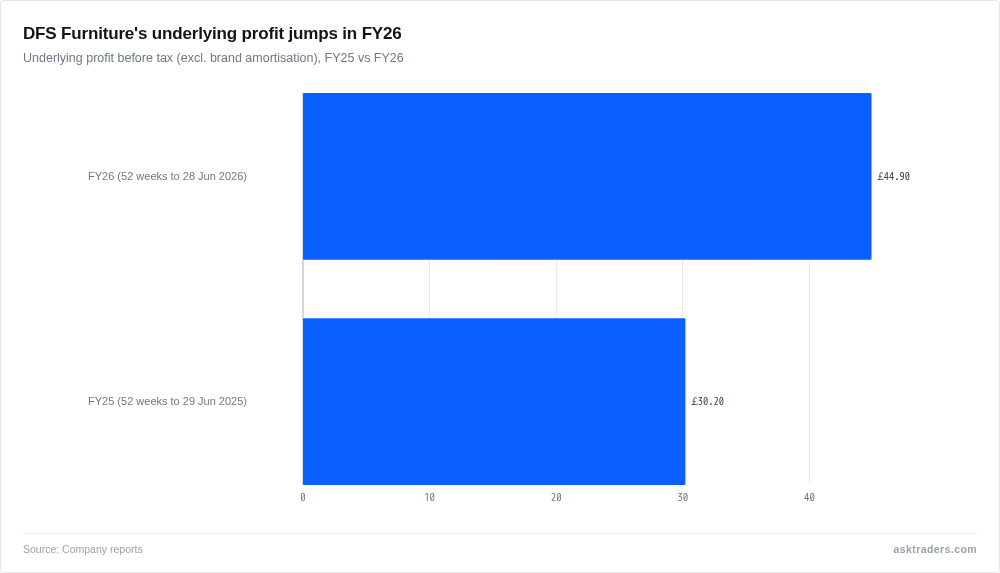
DFS Furniture (LON: DFS), the UK’s largest upholstered furniture retailer, said underlying pre-tax profit rose 48.7% to £44.9m in the year to the 28th of June, meeting the upgraded guidance it had given during the year.
The group, which owns the dfs and Sofology brands alongside its own delivery arm, published the figures in a stock exchange announcement earlier today.
Shares in DFS were trading at 146.5p in early dealing today, up 1.0% from yesterday’s close of 145.0p, after opening at 144.0p. The stock had ranged between 142.0p and 146.5p since the results landed this morning.
DFS had entered the year needing to show it could grow profit and repair its balance sheet against a soft market for sofas and upholstered furniture. On both counts it delivered: gross margin reached the group’s 58% strategic target, up from 56.5% a year earlier, while underlying pre-tax profit climbed from £30.2m.
Net bank debt fell £38m to £69.0m, taking leverage down to 0.9 times net debt to EBITDA, from 1.4 times a year earlier and well below the 2.5 times peak reached in FY24. That balance-sheet repair gave the Board room to reinstate the ordinary dividend at 3.0p for the year, its first payout in two years, covered 4.6 times by earnings.
The performance delivered in FY26 demonstrates the fundamental strength, agility and resilience of the DFS Group. By maintaining disciplined cost management, improving gross margins to 58% and empowering our colleagues through data and technology, we delivered robust earnings growth and significantly strengthened our balance sheet.
Tim Stacey, DFS Furniture
The underlying market stayed weak, though. Group order intake, the value of new customer orders taken, fell 1.0% year-on-year, with the second half down 4.4%. The Sofology brand outperformed with intake up 2.6%, while the larger dfs brand fell 2.0%.
The first 12 weeks of the new financial year are down 2.5%, and DFS guided to only “moderate” profit growth for FY27, in line with a company-compiled analyst consensus of £48.0m for underlying pre-tax profit. The group said UK upholstery volumes remain around 20% below pre-pandemic levels, with any recovery expected to convert to profit at around a 40% rate.