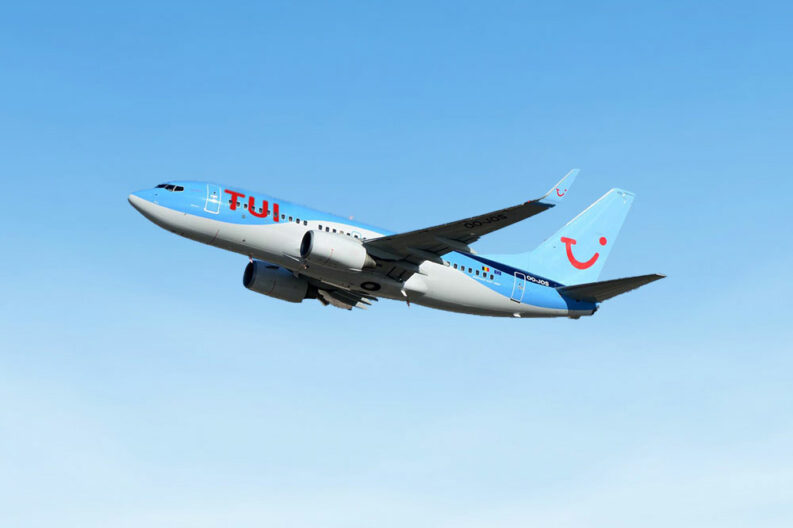
TUI (ETR: TUI1) shares edged higher Tuesday after the travel operator narrowed its full-year profit guidance, pointing to resilient demand despite geopolitical headwinds.
The German group said it now expects fiscal 2026 underlying EBIT of €1.2 billion to €1.3 billion at constant currency, tightening a prior range of €1.1 billion to €1.4 billion, though below the €1,413 million reported in fiscal 2025. Its revenue guidance remains suspended.
TUI, which reports full results on Dec. 9, said it was “on track to deliver robust FY26 underlying EBIT,” helped by strong fourth-quarter demand and improved booking momentum.
Ready to put what you’ve learned into practice?
Try IG’s platform with £10,000 in virtual funds and practise trading
without putting your own money at risk.
Try IG with a demo account →
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Learn the markets with IG Academy
Build your knowledge with IG Academy educational content, then use a
demo account to practise what you’ve learned on the IG platform.
Explore IG →
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
See how trading works before risking real money
IG’s demo gives you access to thousands of markets and £10,000 in
virtual funds, so you can explore the platform and test your ideas first.
Open an IG demo →
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Turn trading theory into practical experience
Learn with IG Academy, explore charts and market tools, and practise
strategies in a simulated trading environment before going live.
Start practising with IG →
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Ready to take your learning further?
IG combines market education, analysis and an established trading platform,
giving you the tools to keep learning as you develop your trading skills.
Discover IG →
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Its Holiday Experiences division, spanning hotels and cruises, remains the growth engine, with capacity expansion and higher rates offsetting the impact of a Jamaica hurricane and Middle East disruption.
Its Markets + Airline business faces softer volumes in the UK and Germany amid a later-booking trend, prompting a 5% cut to own-risk capacity, though average selling prices are holding up. For winter 2026/27, booked revenue is down 7% so far, but TUI said momentum has improved in recent weeks.
The shares rose 0.1%, though they remain down 27.7% this year.
mwb Research analyst Oliver Wojahn reiterated a buy rating and €13.50 price target on the stock, implying about 107% upside from €6.53.
The analyst told investors in a note that the tightened guidance “limits downside” by mitigating geopolitical risks, and that TUI’s proactive capacity management “de-risks full-year operating earnings.”
With the valuation still reflecting heavy geopolitical and macro discounting, he said the risk-reward remains favourable.