
Ithaca Energy has agreed to buy Suncor’s offshore Canadian assets for US$860m in cash plus up to US$250m of oil-price-linked payments, its first deal outside the UK. Its shares were higher in early trade today.
Ithaca Energy (LON: ITH), the North Sea oil and gas producer, has agreed to buy Suncor Energy’s offshore Canadian assets, and its shares were up about 2.7% in early trading today. The company announced the deal at 7am UK time, before the market opened.
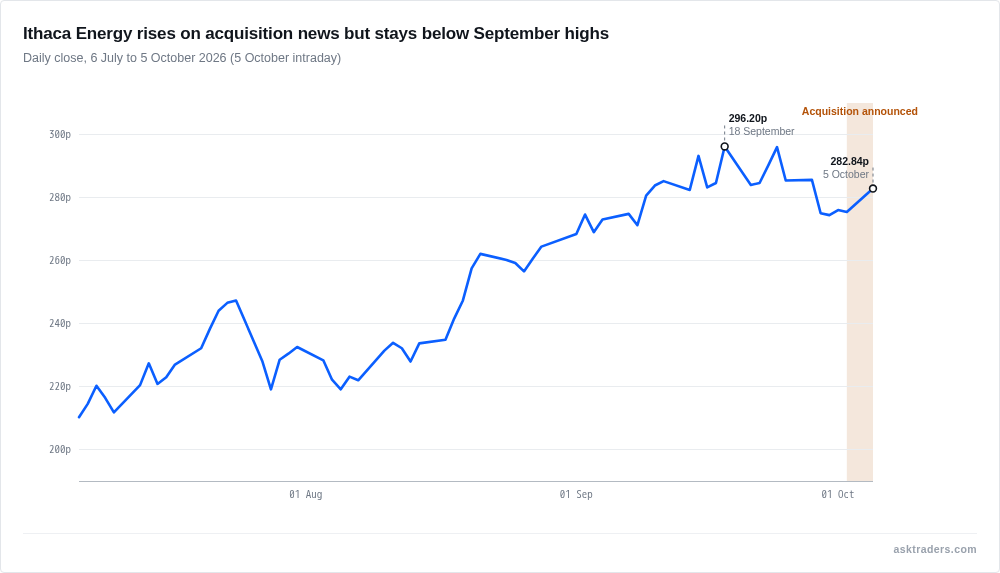
The shares stood at 285.20p at 9.52am UK time, a delayed quote, against Friday’s close of 275.4p. They had opened at 279.4p, up 1.45%. The stock joined the FTSE 100 on the 21st of September and is 5.3% below its intraday peak of 298.6p on the 24th of September.
Ithaca says it is buying a 48% operated interest in the Terra Nova field, plus non-operated stakes of 40% in White Rose Existing Lands and 38.6% in White Rose Growth Lands, which include the West White Rose Extension. Cenovus operates White Rose. The US$860m cash price carries an economic effective date of the 1st of July.
The extra US$250m is contingent on Brent crude. Payments are made if average Brent exceeds US$80 a barrel over the 12 months to the 30th of June 2027, with lower thresholds of US$74 and US$73 in later periods, based on asset production and with a 50% sharing factor. Ithaca will fund them from free cash flow.
By Ithaca’s own estimates, the assets hold 103 million barrels of oil equivalent of proven and probable (2P) reserves, bought at about US$8 a barrel. They should produce about 30,000 barrels a day on average over 2027 to 2031. The company expects immediate gains to cash flow and dividends per share.
Yaniv Friedman, Ithaca’s Executive Chairman, framed the deal as a new phase for the group.
This acquisition marks the next era of growth for Ithaca Energy as we make our inaugural international acquisition in Offshore East Coast Canada.
Yaniv Friedman, Ithaca Energy
Funding comes from cash, an undrawn reserve-based lending facility of US$1.3bn plus US$500m for letters of credit, and secured debt in Canada. Ithaca says leverage will rise but stay well below its ceiling.
Completion is targeted for the first half of 2027, subject to Canadian approvals, with an outside date of the 31st of December 2027 and a US$50m break fee. Ithaca takes on all decommissioning obligations.


