
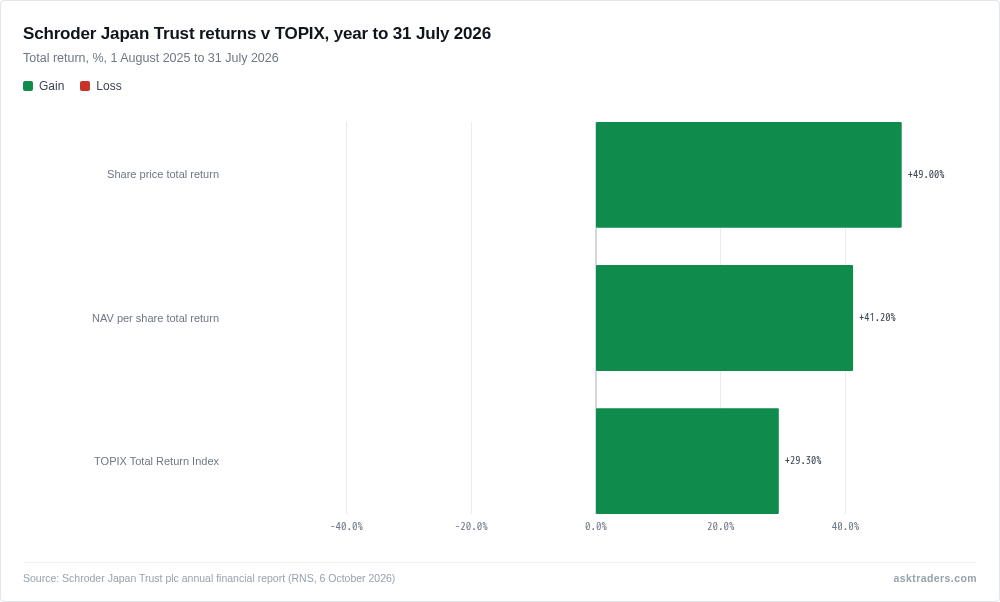
Schroder Japan Trust (SJG.LSE), a London-listed trust investing in Japanese companies, returned 49.0% to shareholders in the year to the 31st of July. Its annual results, published at 7am today, show that beat the 29.3% total return on the TOPIX, Japan’s broad stock index.
The portfolio itself returned 41.2% on a net asset value (NAV) basis, meaning the value of its holdings per share. Over three years the trust has returned 23.1% a year, against 16.4% for the index. It held 66 companies at the year end.
Manager Masaki Taketsume credited stock selection among smaller and mid-sized companies, gearing (borrowing to invest) and AI-linked holdings such as Ibiden. Not owning AI names Advantest and Murata held returns back.
The biggest contributors were Ibiden (+3.2%), Fujikura (+2.7%), JX Advanced Metals (+2.3%), Nintendo (+1.4%) and Rigaku (+1.2%). The main detractors were Advantest (-1.3%), MUFG (-1.1%), Asahi Group (-1.0%), Murata (-1.0%) and LY Corp (-0.9%).
Shareholders did better than the portfolio, by about 7.8 points, largely reflecting the discount of the share price to NAV narrowing to 8.3% from 12.8%. The trust bought 1,750,001 shares into treasury at an average discount of 10.7%. NAV per share reached 406.76p from 298.35p, and net assets £462.7m from £344.6m.
The dividend policy paid out 4% of average NAV, a yield of 3.25% at the 31st of July, with dividends declared quarterly. Gearing ended at 11.9% against 13.4% at the start, within its 10% to 17.5% range, and helped returns.
Yen weakness trimmed returns for UK investors, though they stayed substantial in sterling. Manager Masaki Taketsume was cautious on what comes next:
“The strong rise over the past year means that headline valuations are no longer as appealing as they were, and near-term returns are likely to be more dependent on earnings growth than on further broad-based multiple expansion.”
Masaki Taketsume, manager
Chair Philip Kay said the environment is “particularly well suited to active stock pickers”. The report lists fiscal concerns, Bank of Japan tightening, Middle East tension, tariffs and AI spending as risks.
A conditional tender offer is proposed: if the trust fails to match the benchmark over five years from the 31st of July 2024, a tender for 25% of shares at NAV less costs would follow. After two years the trust is 20.8% ahead. The AGM is at 1.00pm on Friday the 6th of November.


