
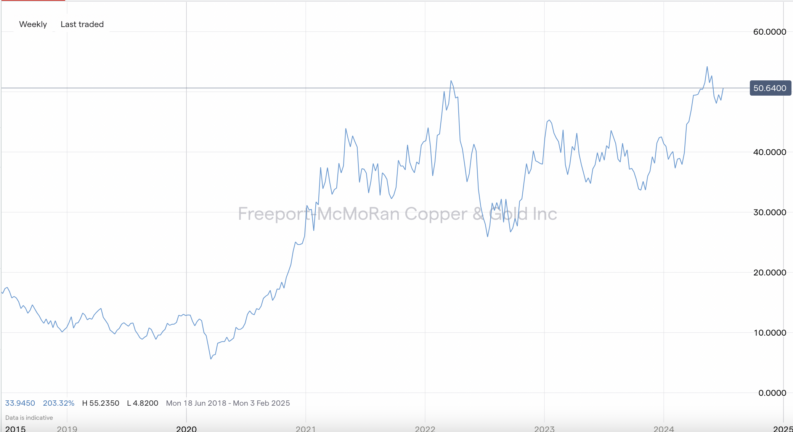
The surging price of copper has resulted in many investors taking up positions in copper mining stocks to capture any more possible bonanza-style price moves. One prime target has been Freeport-McMoran (FCX), the Phoenix, Arizona based mining giant, which between March 2020 and May 2021, saw its share price surge by more than 740%.
It’s a relatively high-risk proposition and this Freeport-McMoRan stock forecast will outline the short- and long-term prospects for the firm. Nothing is ever guaranteed in the markets, but by using a combination of technical and fundamental analysis tools, this analysis will try to answer the question, is Freeport-McMoRan a good stock to buy?
Where Will Freeport-McMoRan’s Stock Price Be in 12 Months?
Increased interest in copper and copper stocks is, to a large extent, driven by the use of the metal forecast to increase as the world moves away from carbon dependency. More than 65% of the world’s copper is used to deliver electricity and with electric vehicles and renewable energy predicted to be growth sectors, there is every likelihood that the price of copper could continue to rise.
Commodity markets and the price of copper remain exposed to external shock factors, which could come into play at any time. However, based on current market conditions, the average price forecast made by Wall Street analysts for the FCX share price is $52.20. The highest target among the analysts polled is $60.54, while the lowest is $41.91.
For now, any good news about the FCX share price looks to be already baked in. The substantial price rise over the last few years has been beneficial for early-door investors, but chasing the stock at current levels due to FOMO could be a costly experience. Even so, most analysts remain bullish.
Support for the FCX stock price also comes in terms of the firm returning some of its profits to investors. The healthy balance sheet has resulted in dividend payouts, with the current dividend yield at around 0.59%.
The firm is far from being considered a high-yield, blue-chip stock—its sector is too inherently risky for it to be treated in the same way as Procter & Gamble and Walmart.
Overall, analysts are primarily bullish, with 15 of 24 assigning the stock a Buy rating. The remaining nine have given FCX a Hold rating.
Freeport-McMoRan News
In early July, the company announced that its Indonesian subsidiary, PT Freeport Indonesia (PT-FI), had completed construction of its new Manyar smelter in Gresik, Indonesia, in June 2024 and has commenced commissioning operations.
FCX also announced that PT-FI’s prior concentrate and anode slime export licenses expired on May 31, and PT-FI did not export copper concentrates or anode slimes during June 2024. As a result of the delay in obtaining PT-FI’s export license, FCX expects a portion of its second-quarter 2024 production will be shipped in future periods.
In April, Freeport-McMoRan beat Wall Street estimates for first-quarter profit, boosted by increased production and easing costs. The company revealed quarterly production of copper rose to 1.1 billion pounds from 965 million pounds a year earlier. This was aided by a 49% rise in output from its Indonesia operations.
Who is Freeport-McMoRan (NYSE: FCX)?
Freeport-McMoRan Copper & Gold Inc is a New York Stock Exchange-listed stock, which operates under the ticker FCX and has a market capitalisation of approximately $50bn.
It’s one of the larger firms in the copper sector and has the additional advantage of a considerable proportion of its reserves being US-based. Geopolitical risk always casts a shadow over commodity markets and being US-based means it offers a security of supply to US manufacturers, which some competitors just can’t match. It does have operations in Indonesia and South America but is, from an investment perspective, at least still largely seen as a US miner.
Extracting minerals and metals from the ground always leads to a range of by-products also being found. FCX, therefore, does have some operations that produce gold and molybdenum, but in relation to most of its peers, the firm is very much an out and out copper miner.
The firm’s value isn’t based on clever intellectual property rights relating to the processing of the metals or speculative exploration projects in South America. Instead, the major price drivers of Freeport-McMoran stock predictions are its prospects as a large scale miner with operations in the US that account for 60% of total national copper production. The firm has substantial copper reserves and is so closely related to the fortunes of the metal that the FCX share price closely mirrors moves in the price of copper when it is traded on commodity exchanges.
Freeport-McMoRan Long-Term Forecast
The Freeport-McMoRan long-term stock forecast is, to a greater degree, influenced by the actions of the firm and its plans to develop its reserves. In addition, the price of copper is obviously key.
Freeport-McMoRan’s long-term trajectory heavily relies on copper prices. As a major copper producer, a strong copper market translates to increased revenue and profitability for FCX. According to Goldman Sachs, copper is expected to reach $12,000 a ton by the end of 2024, driven by rising demand for renewable energy and electric vehicles. This forecast bodes well for Freeport-McMoRan’s long-term prospects.
However, there are uncertainties. Geopolitical instability and potential disruptions to supply chains could cause copper prices to fluctuate. Additionally, competition from other copper producers and the discovery of new copper mines could put downward pressure on prices.
Overall, Freeport-McMoRan is well-positioned to benefit from the long-term growth in copper demand. However, investors should closely monitor copper price movements and factors affecting global supply chains..
Is Freeport-McMoRan a Good Buy?
A lot of the good news for copper stocks is already priced into the FCX share price. Buying stock at these levels could enable investors to take advantage of any future surge in the price of copper, but the current trading range suggests investors would do well to apply a degree of patience and aim to achieve an elegant exit.
It would also be worth applying the fundamentals of risk management. All speculative investments should be made using amounts of money that are small enough that they can afford to be lost, completely. That rule particularly applies to mining companies where stock prices are subject to dramatic price swings in the global commodity markets. When a firm has a share price closely correlated to one asset – copper – then the risks (and returns) are intensified.
Another potential curveball to factor in is investor appetite for the mining sector. While the world’s population craves the products the metals make, there is a notable shift towards more ethical and ecologically aware investing.
To its credit:
“FCX is a founding member of the International Council on Mining and Metals (ICMM). Implementation of the ICMM Sustainable Development Framework across the company results in site-level sustainability programs that meet responsible sourcing objectives”.
(Source: FCX)
Mining might not be the greenest of businesses, but FCX is making a committed effort to being one of the greenest firms in the sector. Sometimes being the least bad option can pay off, and big institutions with investment mandates to make returns, but also balance out ethical concerns, may not be completely put off investing in FCX stock thanks to the demonstrable efforts the firm is making.