
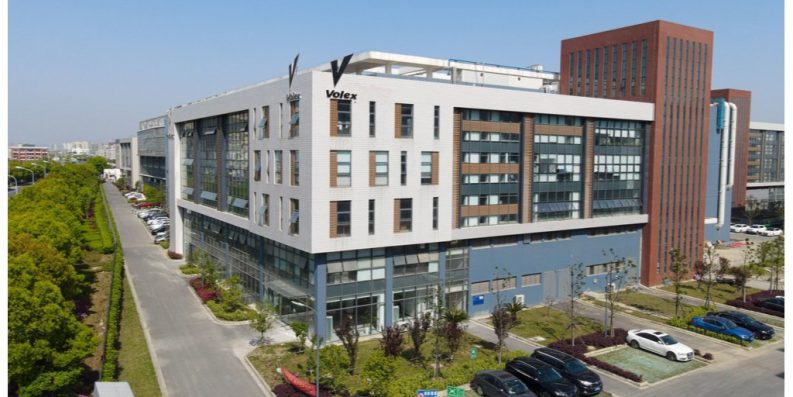
Volex (LON: VLX), a specialist manufacturer of critical power and data transmission products, has seen its shares slide around 2.7% in early Monday trading despite the company expecting record first-half revenue of at least $710m and has guided full-year profit towards the upper end of market expectations.
Its trading update, issued today, covers the six months ended 30 September and says every end-market grew.
The figure includes about $11m from Kepler SignalTek (KST), acquired in July. Organic constant currency growth, which strips out acquisitions and exchange-rate swings, is at least 21%, down from the 28% reported for the first four months. Volex says data centre programmes are now annualising, and calls the sequential comparison the better guide: organic constant currency revenue is about 7% above the second half of FY2026.
Data Centre revenue was well ahead of a year earlier but below the second half of FY2026. Volex said in March that period had been lifted when it secured key components early and temporarily took a larger share of customers’ needs while other suppliers could not deliver.
Supply has since normalised, underlying demand is strong, and the board’s medium and long-term view is unchanged. Volex expects next-generation, higher-speed products to ramp up during FY2028.
EV & Electrification grew very strongly, principally because Volex now supplies a greater share of its largest EV customer’s requirements, reflecting its competitive position after investing in vertical integration.
Complex Industrial Technology also grew significantly, led by aerospace and defence. Customers took extra deliveries to build buffer stock while Volex consolidates its US manufacturing sites, bringing forward about $10m of revenue that would otherwise have landed in the second half. The consolidation is on track to finish by the end of the financial year.
Off-Highway grew well despite a prior-year comparison that included a one-off customer project. Consumer Electricals returned to organic growth on new domestic appliance projects, and Medical posted modest organic growth.
Volex expects first-half underlying operating margin to show progress towards its medium-term 12% target, helped by mix, higher-margin KST and efficiencies. Leverage was no more than 1.2x at 30 September, and it had spent £16.9m of its £20m buyback by then.
Consensus as at Friday points to FY2027 underlying operating profit of $150.4m, within a $145.9m to $153.3m range, on revenue of $1,386.2m. Half-year results are due on the 12th of November.