
XP Power (LON: XPP) reported Q3 order intake of £106.8m, up 93% on a year earlier, and guided FY27 slightly ahead of market expectations. The maker of power controllers for chip-equipment, healthcare and industrial customers calls the intake a record. FY26 expectations are unchanged.
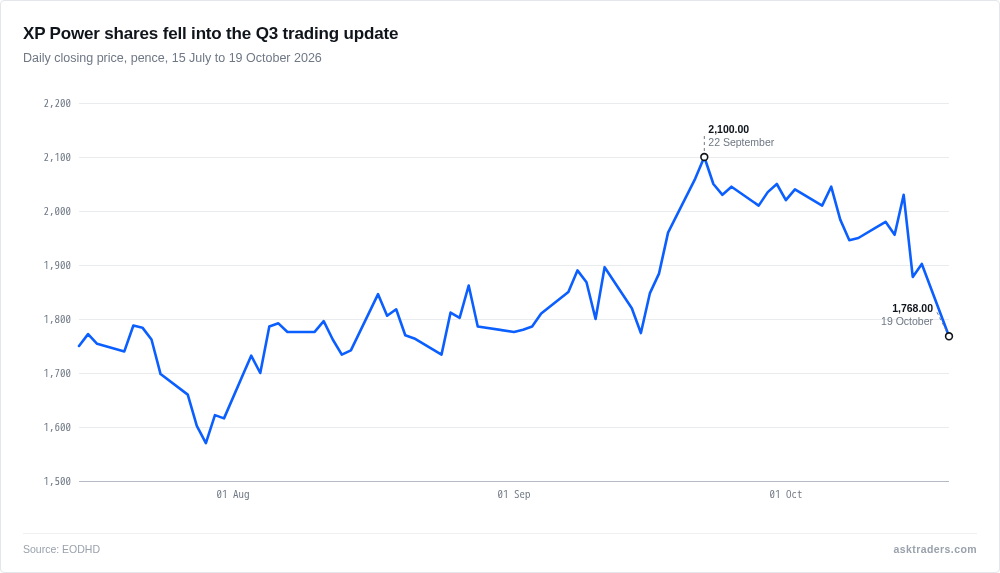
The shares were 1780p at 9.12am, a delayed quote, up 0.7% on yesterday’s close of 1768p. Today’s session opened at 1704p, 3.6% lower, and touched 1590p before recovering. The close had been 2030p last Wednesday.
The company said order intake was 22% above the previous quarter and broad-based, led by makers of semiconductor manufacturing equipment and industrial technology. It added that some customers ordered earlier than usual because industry lead times are lengthening, and that underlying demand is similar to Q2.
Book-to-bill, orders received divided by revenue billed, was 1.67x against 0.96x a year earlier. Revenue of £63.8m, against £57.6m, was in line with the company’s expectations. A one-off £3.7m US tariff refund reduced reported revenue, which would have been £67.5m without it, consistent with the £135m guided for the second half. Vietnam shipments were 70% higher than in Q2.
| Metric | Q3 2026 | Comparison period | Change |
|---|---|---|---|
| Order intake (£m) | 106.8 | 55.3 (Q3 2025) | 93% reported |
| Revenue (£m) | 63.8 | 57.6 (Q3 2025) | 11% reported |
| Book-to-bill | 1.67x | 0.96x (Q3 2025) | 0.71x |
| Net debt (£m) | 4.5 | 47.7 (30 June 2026) | None given |
| Order book (£m) | 216.9 | None given | None given |
Net debt, borrowings minus cash, fell to the £4.5m shown from £47.7m at the 30th of June, after £50.2m arrived when the Comet litigation bond was released. XP Power expects net cash in Q4 and will keep defending the Comet case.
The FY27 guidance is measured against company-compiled analyst forecasts, as of yesterday, of £35.9m adjusted operating profit and 75.4p adjusted earnings per share. Management said it expects revenue growth and operational leverage, profit growing faster than revenue, to deliver FY27 performance slightly ahead of those expectations.
The improving revenue momentum and order book visibility increase our confidence for FY27.
XP Power
FY26 results are due on the 2nd of March.