

Standard Chartered raised its 2026 income guidance today after third-quarter pre-tax profit climbed 29% at constant currency to $2.25bn. Reported growth was 27%. Income rose 14% at constant currency and 13% as reported to $5.8bn, and return on tangible equity hit 15.7%, up from 10.5% a year earlier.
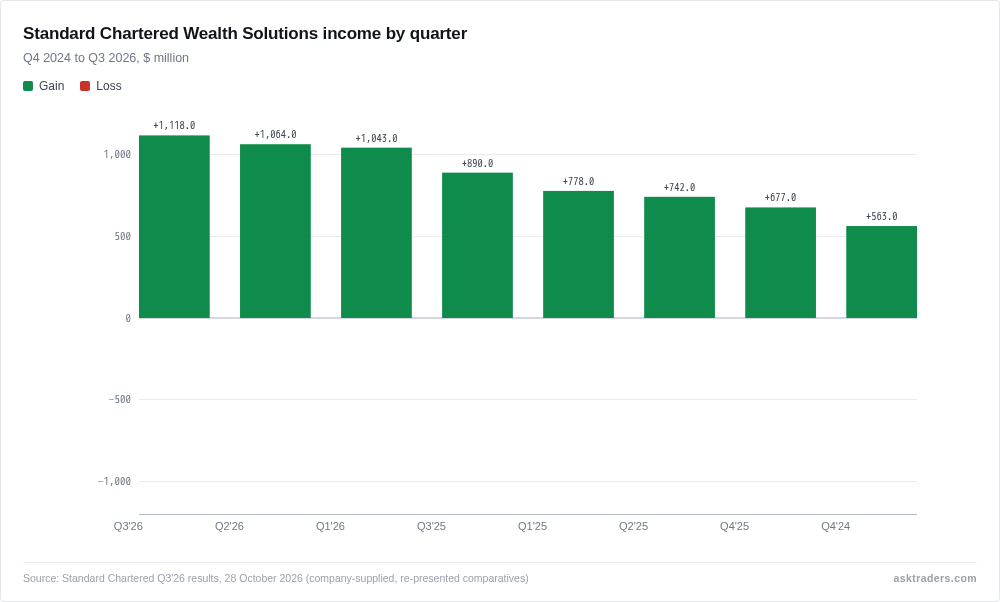
Wealth was the engine. Wealth Solutions income reached $1,118m, up 26% and a third straight record quarter, as the London-headquartered bank took in a record $20bn of affluent net new money and 76,000 new-to-bank clients.
Trading helped too. Global Markets income rose 21% at constant currency to $1,014m, with flow income up 21% and episodic income up 13%.
Not every line grew. Deposits & Mortgages slipped 1% as Hong Kong’s Best Lending Rate cap restricted mortgage repricing, unsecured lending fell 13% at constant currency on tighter credit standards, and Capital Markets & Advisory fell 4% at constant currency on slower M&A.
Costs rose 9% at constant currency, so jaws, the gap between income and cost growth, stayed positive at 5%. Central items lost $334m, including a $45m provision for potential legal action over a historical transaction in a legacy business.
Credit impairment fell to $90m from $188m, a loan-loss rate of 9 basis points. That includes a $34m net charge from Middle East conflict overlays, and the bank lifted the weighting on its downside scenarios to 60% from 41% at the end of 2025.
The common equity tier 1 (CET1) ratio, a core capital measure, was 13.8%, down 31 basis points on the quarter and 3.6 points above the regulatory minimum. Buybacks are shrinking the share count: $484m bought 16 million shares by the 30th of September, under the $1.0bn programme launched on the 29th of July.
Shares in issue stood at 2,174m, against 2,293m a year earlier, and basic earnings per share rose 55% to 68.9 cents. A lower Pillar 2A requirement will cut the CET1 requirement by 30 basis points from 1 January 2027.
The bank now expects 2026 income growth above its 5-7% range at constant currency, excluding notable items, with net interest income up about 4%, cost-to-income near 60% and return on tangible equity around 14%.
“We delivered another strong quarter, with broad-based growth across our businesses and year-to-date earnings per share up 27%.”
Bill Winters, Group Chief Executive