


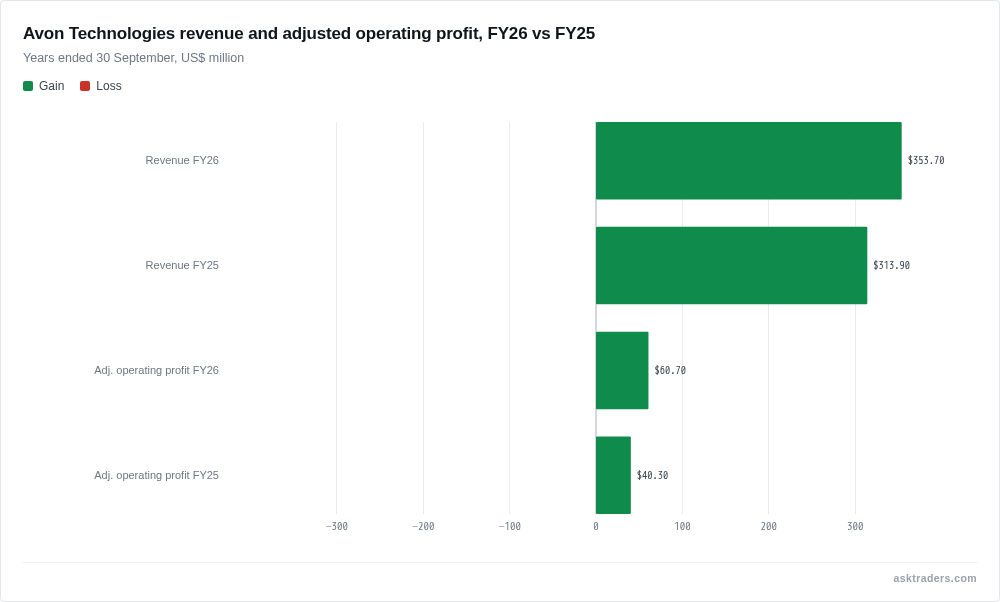
Avon Technologies (LON: AVON), the maker of protective helmets and respiratory equipment, reported a 50.6% jump in full-year adjusted operating profit to $60.7m. Revenue rose 12.7% to $353.7m in the year to the 30th of September, and the results were published at 7:00am UK time today.
The adjusted operating margin widened to 17.2% from 12.8%, and adjusted basic earnings per share climbed 57.1% to 143.3c. The total dividend rises 8.9% to 26.8c, with an 18.7c final payable on the 26th of February 2027 to shareholders on the register at the 5th of February.
Chief executive Jos Sclater said the year marked the completion of the company’s STAR transformation programme:
FY26 was a significant year for Avon. We completed our STAR transformation programme, exceeded all our medium-term targets a year ahead of plan and continued to deliver for our customers.
Jos Sclater, chief executive, Avon Technologies
STAR, together with a record year at Team Wendy, the helmet division, underpinned the improvement. Team Wendy shipped more than 200,000 helmets and lifted its margin to 11.0% from 4.6%, with adjusted operating profit of $17.9m against $6.7m. Filter volumes also hit a record. The company said one-off benefits, including US tariff refunds and tax incentives, also helped, without quantifying them.
Cash improved alongside profit. Free cash flow, the cash left after running costs and investment, reached $30.9m from $12.6m. Net debt excluding leases fell to $33.7m from $50.1m, and leverage, net debt relative to earnings, fell to 0.43 times from 0.86 times. Return on invested capital was 27.6%.
The forward indicators are more modest. Orders were flat at $353.6m, against $351.5m a year earlier, and the order book, work contracted but not yet delivered, was $262.7m against $262.8m. Avon Protection’s orders fell to $184.1m from $213.8m, with the prior-year comparative including Ukraine-related system orders.
For FY27 Avon guides to mid-single-digit revenue growth, a margin of 16% to 18% and free cash flow of about $50m to $60m. It named Team Wendy production consistency and a US post-mid-term stalemate as risks, while targeting more than $600m of revenue within five years.