

Big Yellow Group (LON: BYG), the UK’s largest self-storage operator, fell as much as 6.9% today after reporting a £213.1m half-year loss and weaker occupancy since September. The results came out yesterday evening, after the market had closed.
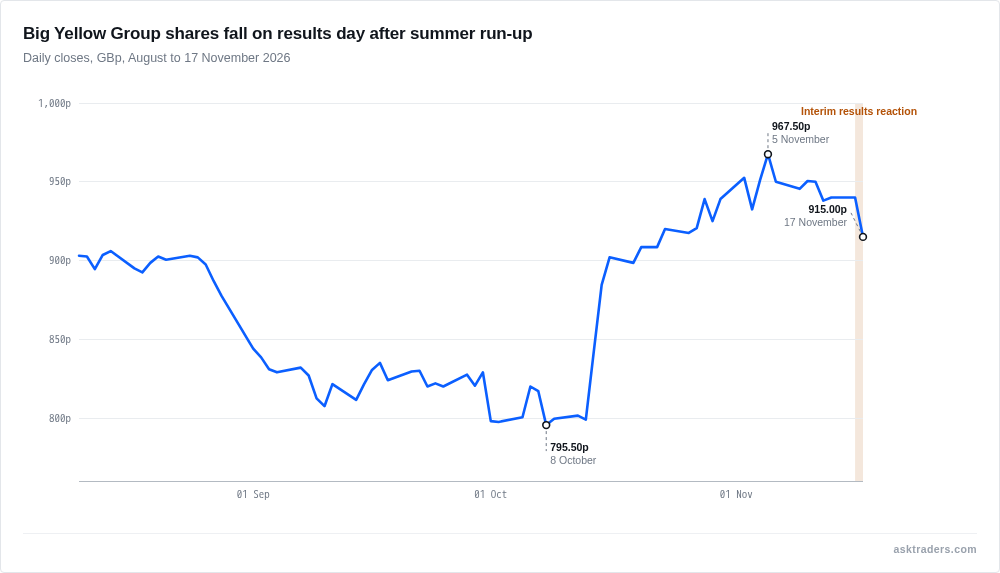
The shares closed at 915p, down 2.66% from 940p on Monday, after opening at 899.5p and touching 875.5p. They had risen about 18% from a low close of 795.5p on the 8th of October before the results.
The loss before tax compares with a £74.8m profit a year earlier. The cause is a £271.7m revaluation deficit, a paper fall in the valuer’s estimate of the stores’ worth rather than cash lost. Higher cap rates (annual rent as a share of property value) and discount rates followed the rise in gilt yields, and net asset value per share fell 10% to 1,176.1p.
Executive Chairman Nicholas Vetch CBE put the write-down down to interest rates.
It is inevitable that as interest rates rise property values will fall, as they have; and these falls are not confined to self storage assets.
Nicholas Vetch CBE, Big Yellow Group
Strip out revaluation and the business was flat. Revenue rose 4% to £109.2m, but adjusted profit before tax was £59.4m against £59.6m, as higher property rates and less capitalised interest absorbed the rental growth. Adjusted earnings per share were 29.7p (30.0p) and the dividend was held at 23.8p.
The worry is occupancy. Like-for-like occupancy was 77.7% at the end of September, 0.3 points behind last year. Since then the group has lost 65,000 sq ft, against 25,000 sq ft a year earlier, widening the gap to 1.1 points. New customers are paying 2% less than a year ago.
Brokers split, according to Proactive Investors. Panmure Liberum kept its “buy” rating and 1,150p target but called the results disappointing, saying the 31.4p of second-half earnings per share needed for its 61.1p full-year forecast looks increasingly ambitious. Peel Hunt, with an “add” rating and a 900p target, called them broadly in line and unlikely to change forecasts.
Vetch said demand in the domestic customer segment had been soft, given low housing market activity and mortgage approvals. The interim dividend goes ex-dividend on 31 December.