

Debenhams Group (AIM: DEBS), the online retailer formerly known as boohoo, reported a first-half pre-tax profit of £28.3m today, its first since August 2021. A year earlier it lost £17.9m.
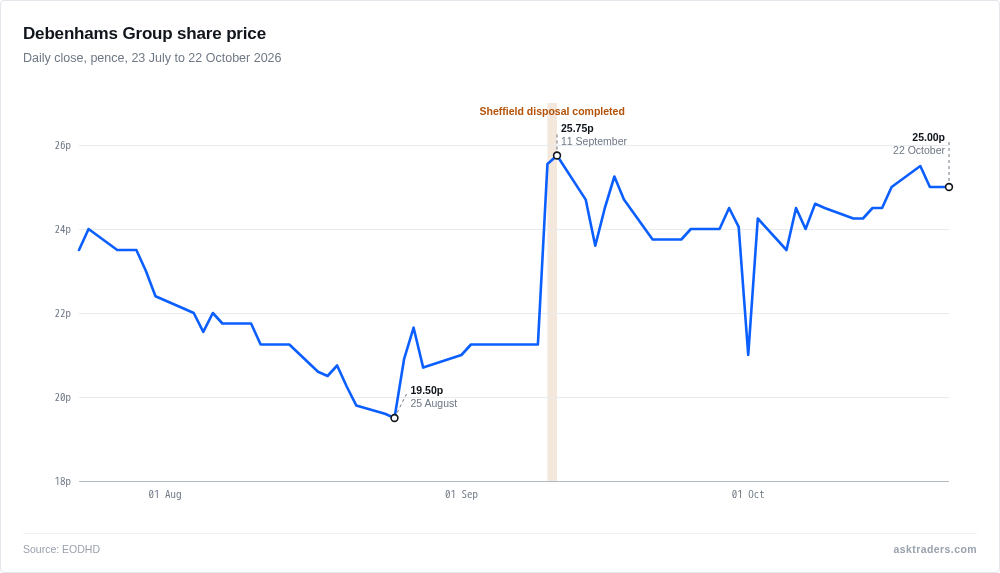
The shares were 26.0p at 08:01 UK time, on a delayed quote, up 4.0% on yesterday’s close of 25.0p, with the low so far at 25.5p. Since the start of January the range has run from 16.5p in April and May to 27.0p intraday on the 11th of September.
The quality of that profit is the catch. It rests on a non-cash credit of about £40m from the sublease of a US distribution centre, and last year’s period had a £34.3m credit tied to Daventry. Strip out both and the loss before tax still narrowed, from about £52m to about £12m. Without the credit, the group would not have reported a profit.
The operating picture did improve. Gross merchandise value (GMV, sales before returns) rose 1.8% to £863.8m, with growth accelerating from 0.5% in the first quarter to 2.9% in the second. The Debenhams brand, about 42% of the total, grew 14.1%, PLT, boohoo and Karen Millen all returned to growth, while MAN fell 28.0%. Revenue slipped 3.0% to £409.6m.
Adjusted EBITDA (earnings before interest, tax, depreciation and amortisation, excluding one-offs) rose 14.6% to £24.0m. Other measures against last year:
| Measure | H1 FY27 | H1 FY26 |
|---|---|---|
| Gross margin | 54.1% | 51.9% |
| Reported EBITDA | £19.7m | £3.5m loss |
| Pre-tax result | £28.3m profit | £17.9m loss |
| Free cash flow | £5.6m inflow | £22.1m outflow |
| Net debt | £98.5m | £111.1m |
Gross margin gained 220 basis points, while marketplace sales, from third-party sellers, reached 38.9% of GMV from 32.7%.
Two disposals drive the balance sheet. Assigning the Sheffield lease to Primark Stores for £90m completed on the 10th of September, with £76.5m received and £13.5m due in early 2027. Nasty Gal was sold on the 15th of September for $16m (£11.9m).
“…net debt is expected to be negligible at year-end. This is significantly ahead of our original guidance provided at the start of the year.”
Dan Finley, Group CEO
That excludes any Burnley proceeds. The company reiterated full-year Adjusted EBITDA of no less than £59m, said September trading was good with growth accelerating further, and kept its medium-term ambition of £100m-plus pre-tax profit.
Looking to FY28, the company expects depreciation to fall to £14m from £22m, lease costs to £4m from £14m and interest to drop by at least about £10m, and it points to brought-forward tax losses of over £200m.