

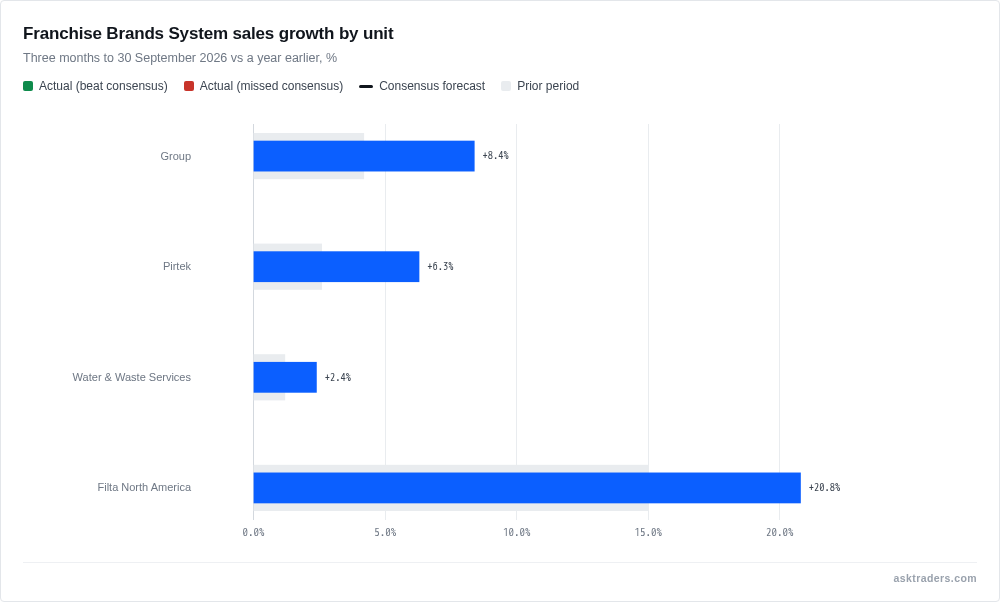
Franchise Brands (AIM: FRAN) reported record third-quarter System sales growth of 8.4% today, up from 4.2% in the same period of 2025. The AIM-listed group runs international franchise brands in essential services through a mobile workforce. System sales are sales across its whole franchise network, and growth in the first half was 6.7%.
Pirtek grew System sales 6.3% in sterling, against 2.6% a year earlier. The UK rose 8.9% (1.5%), Germany 5.0% in local currency (0.6%) and Benelux 14.0% in local currency (1.1%).
Water & Waste grew 2.4%, up from 1.2%. Metro Rod performed well, the company said, but growth was held back by the previously announced deferral of some Willow Pumps projects into the fourth quarter.
Filta North America rose 20.8% in local currency, up from 15.0%, the strongest figure among the units reported. Excluding used cooking oil (UCO), growth was 15.9%, against 11.6%.
UCO sales rose 42.3% (32.9%), and price did most of the work: prices added 29.9% (18.1%) while volumes added 9.6% (12.5%). The company expects the UCO market to stay structurally supported around current levels into 2027. FiltaClean Pro started well, with its first national account onboarded for a leading quick service restaurant group.
Stephen Hemsley, Executive Chairman, linked the quarter to the strategy and to the outlook:
Despite the environment remaining challenging, the strategic actions we have taken are delivering clear results, underpinning our confidence that our full-year performance will be in line with market expectations.
Stephen Hemsley, Executive Chairman
That strategy is to simplify the group around Pirtek, Filta and Metro Rod, and implementation is in line with expectations. Any disposal proceeds will go towards faster debt repayment. Capital allocation centres on cutting debt, with strong cash conversion from the capital-light model and more attention on working capital.
Guidance is in line with market expectations. Adjusted EBITDA (earnings before interest, tax, depreciation and amortisation) for the year to 31 December 2026 is expected to match market expectations of £36.5m to £38.0m, with consensus at £37.0m. That assumes no improvement in market conditions in the fourth quarter.