


Halma (LON: HLMA), the FTSE 100 group of about 40 safety, environmental and healthcare technology companies, reported record half-year results today, with adjusted EBIT up 22.5% to £345.4m. The shares were up 1.82% in early trading.
The stock was quoted at 3,468p at 9.03am, up 62p on yesterday’s close of 3,406p. The results came out at 7am, before the market opened, so the timing fits a positive reaction. That is timing only. The shares remain about 29% below their 6-month high of 4,902p, reached on the 3rd of June.
Revenue for the six months to 30 September rose 15.8% to £1,433.2m. Adjusted EBIT, which strips out acquisition-related and one-off items, rose from £282.0m a year earlier, or 26.4% excluding a one-off licence deal at its Nuvonic business last year. The interim dividend rises 7% to 10.30p. Group Chief Executive Marc Ronchetti said:
We delivered an excellent first half, with record revenue and profit, strong growth across all three sectors, a very strong Adjusted EBIT margin and returns well above our cost of capital.
Marc Ronchetti, Group Chief Executive, Halma
Most of the growth came from Environmental & Analysis, where organic revenue (excluding acquisitions, disposals and currency) rose 18.0%. Photonics sales grew about 30% organically, driven by optical switches for a hyperscaler, a very large data-centre operator. Safety grew 10.1% organically and Healthcare 5.8%. The adjusted EBIT margin was 24.1%, against 22.8% a year earlier.
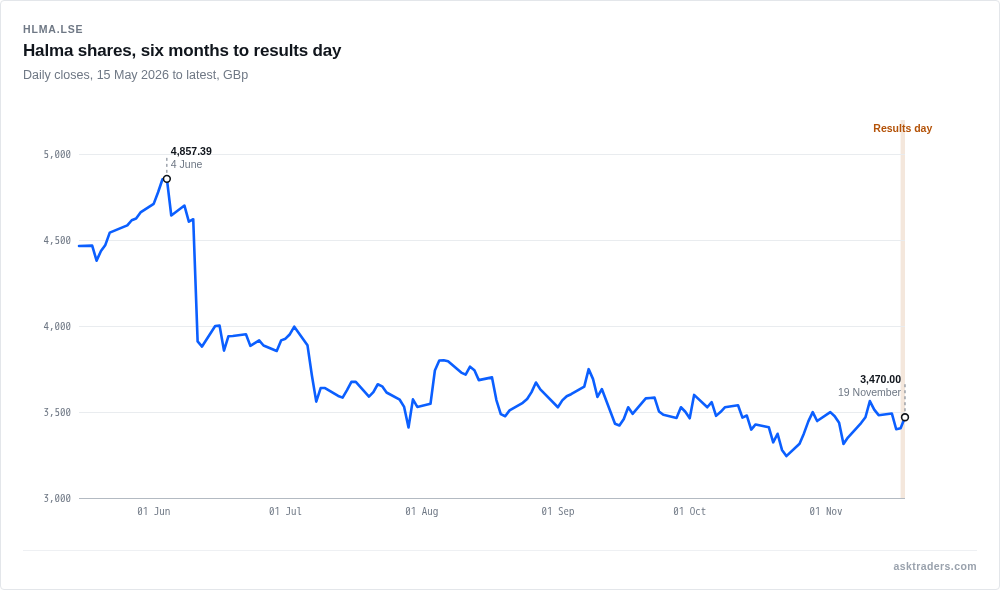
Guidance is unchanged: low double-digit organic growth at constant currency, and an adjusted EBIT margin of 23.5% to 24%. By our inference, that looks cautious, because the first half is already ahead on both measures, with organic growth of 13.1% excluding the one-off. Halma does not call its guidance conservative. It says order intake is ahead of revenue and that it has made a good start to the second half.
The caveats are concentration and debt. The hyperscaler customer was 22% of group revenue, up from 20% in 2025/26, and net debt rose to 1.26 times adjusted EBITDA from 1.16 times in March after record acquisitions of £516m. Management describes end-market conditions as varied.