

Lloyds Banking Group (LSE: LLOY) reported statutory pre-tax profit of £6,625m for the nine months to the 30th of September, up 42% from £4,678m a year earlier. Return on tangible equity, a measure of profit against shareholders’ core capital, rose to 17.9% from 11.9%.
The comparison is flattered by last year, which carried an £800m motor finance charge in the third quarter. Remediation costs fell to £61m from £912m, so total costs dropped 10% to £7,307m. Chief executive Charlie Nunn said the group was on track for its 2026 guidance, alongside a new strategy, Accelerate 2030.
Underlying net interest income, the gap between what Lloyds earns on loans and pays on deposits, rose 10% to £11,084m. The banking margin averaged 3.21% against 3.04%, helped by the structural hedge, which reinvests maturing positions at higher rates. The hedge earned £5.2bn, up from £4.0bn.
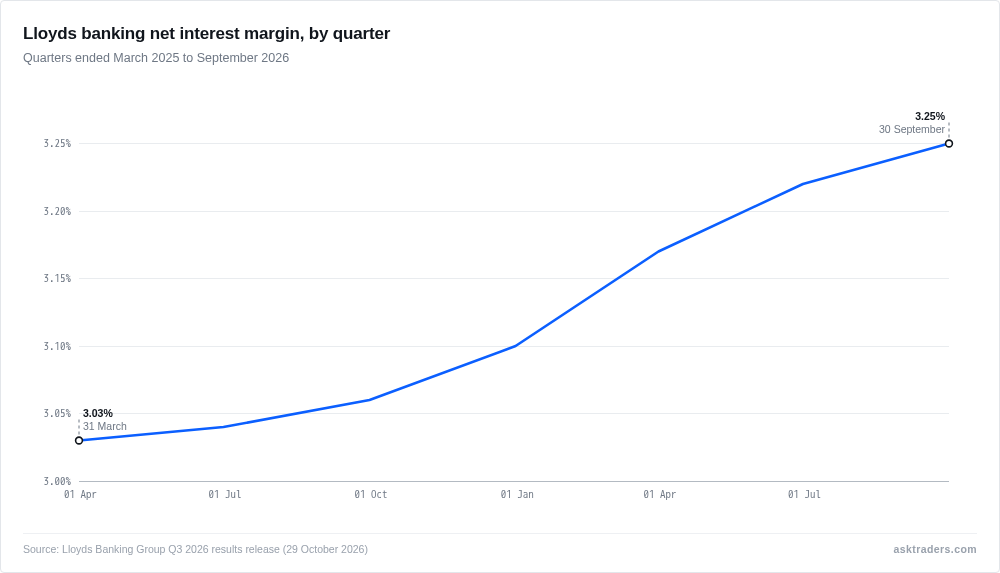
The third-quarter margin reached 3.25%, only 3 basis points above the second quarter’s 3.22%. Lloyds described the trend this way:
continuing positive margin momentum although at a slowing pace
Lloyds Banking Group
Mortgage margin compression and a competitive deposit market offset part of the hedge gain.
Costs were mixed. Operating lease depreciation, tied to its car leasing book, rose 17% to £1,261m, though the third quarter was 7% lower than the second. The impairment charge for bad loans rose to £930m from £618m, including £88m from a revised economic outlook on the Middle East conflict. Arrears stayed low and stable.
The core capital (CET1) ratio stood at 13.3%, down from 13.6% at the end of June, after dividends, the July buyback and the Curve acquisition. The board intends to pay this down to about 13.0% by the end of 2026. A £1.75bn buyback finished on the 24th of September, and a new one of up to £1.0bn began on the 31st of July.
Lloyds kept 2026 guidance, including return on tangible equity above 16%. It said current conditions imply net interest income modestly above its £14.9bn floor.
Motor finance remains open. Four challenges to the regulator’s final redress rules have delayed implementation, with an Upper Tribunal hearing listed for the second half of February 2027. Lloyds said its provision remains its best estimate, and that there have been no further charges relating to motor finance commission arrangements. Full-year results follow on the 28th of January 2027.