

Oxford Instruments (LON: OXIG), the FTSE 250 technology hardware group, reported a 44% jump in first-half orders today. Orders reached £296.0m in the six months to 30 September, against £205.2m a year earlier.
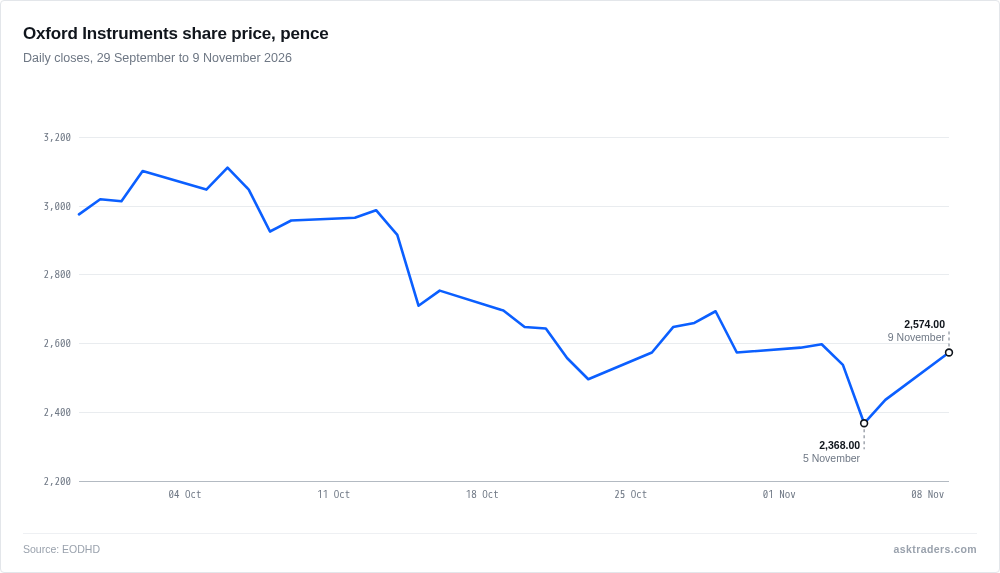
By 9:30am the shares were at 2,644p, 2.7% higher than yesterday’s close of 2,574p, on delayed data. They opened at 2,610p and have traded between 2,594p and 2,728p. Last Thursday, 5 November, they closed at 2,368p, their lowest close in the last 30 sessions.
The Advanced Technologies division drove the increase. Its orders more than doubled to £132.2m from £58.6m, and about 75% of them were for datacom. The company said high-volume manufacturers are choosing its compound semiconductor process technology for datacentre and communications infrastructure, including AI datacentres.
That has swelled the group order book to £317m. Advanced Technologies accounts for about £173m of it, up more than 90% on a year ago, and order cover for the current year is full and runs into the third quarter of FY28.
Adjusted operating profit rose to £30.0m from £24.7m despite a £1.7m currency headwind, lifting the margin to 14.9% from 13.3%. Free cash flow was £19.1m against £0.2m, and net cash stood at £74.8m. The company had spent £83.1m of its £100m buyback by 30 September and intends to extend it by a further £25m to summer 2027. Adjusted earnings per share rose to 42.2p from 32.7p, helped by the smaller share count.
The larger Imaging and Analysis division was steadier. Revenue edged up 2.4% to £142.2m and its margin improved to 18.0% from 17.1%. Semiconductor-related orders rose 59.4%, but group orders from US academia fell 35%, and that sector made up 10% of first-half revenue.
Chief executive Richard Tyson pointed to the order book as the basis for management’s confidence in the year.
given the growth in our order book, we are confident in our ability to meet market expectations for the full year, and are on track for our medium-term goals.
Richard Tyson, chief executive, Oxford Instruments
Full-year trading is in line with expectations, not ahead of them. Company-quoted consensus is revenue of £446.1m and adjusted operating profit of £81.2m. For FY28, Advanced Technologies revenue is expected to grow about 20%, with its margin moving into a 12% to 15% range, assuming lead times of about 12 months are unchanged.
Even after today’s gain, the shares are about 20% below their 52-week high of 3,318p on the 3rd of June. They are up about 29% this year but down 10.6% over the past month. The next trading update is due on the 14th of January.