Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider. You should consider whether you understand how spread bets and CFDs work, and whether you can afford to take the high risk of losing your money.
61% of retail CFD accounts lose money. Don’t invest unless you’re prepared to lose all the money you invest. This is a high-risk investment and you should not expect to be protected if something goes wrong. Take 2 mins to learn more at https://etoro.tw/44JRWLY
CFDs and FX are complex instruments and come with a high risk of losing money rapidly due to leverage. Between 74-89% of retail investor accounts lose money when trading CFDs. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider. You should consider whether you understand how spread bets and CFDs work, and whether you can afford to take the high risk of losing your money.
61% of retail CFD accounts lose money. Don’t invest unless you’re prepared to lose all the money you invest. This is a high-risk investment and you should not expect to be protected if something goes wrong. Take 2 mins to learn more at https://etoro.tw/44JRWLY
CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 74% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider. You should consider whether you understand how spread bets and CFDs work, and whether you can afford to take the high risk of losing your money.
61% of retail CFD accounts lose money. Don’t invest unless you’re prepared to lose all the money you invest. This is a high-risk investment and you should not expect to be protected if something goes wrong. Take 2 mins to learn more at https://etoro.tw/44JRWLY
CFDs and FX are complex instruments and come with a high risk of losing money rapidly due to leverage. Between 74-89% of retail investor accounts lose money when trading CFDs. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider. You should consider whether you understand how spread bets and CFDs work, and whether you can afford to take the high risk of losing your money.
61% of retail CFD accounts lose money. Don’t invest unless you’re prepared to lose all the money you invest. This is a high-risk investment and you should not expect to be protected if something goes wrong. Take 2 mins to learn more at https://etoro.tw/44JRWLY
CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 74% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
AskTraders may earn a commission when you click through to a broker.
Persimmon Shares Rise 6% as Sales Rate Improves
Persimmon's third-quarter update showed homes selling slightly faster and at slightly higher prices in a challenging housing market. The shares rose today, while the company warned that 2027 cost pressures will limit profit growth.
Persimmon (LON: PSN), the housebuilder behind the Persimmon, Charles Church and Westbury Partnerships brands, said trading since 1 July is in line with market expectations. Its shares rose sharply in London after the update.
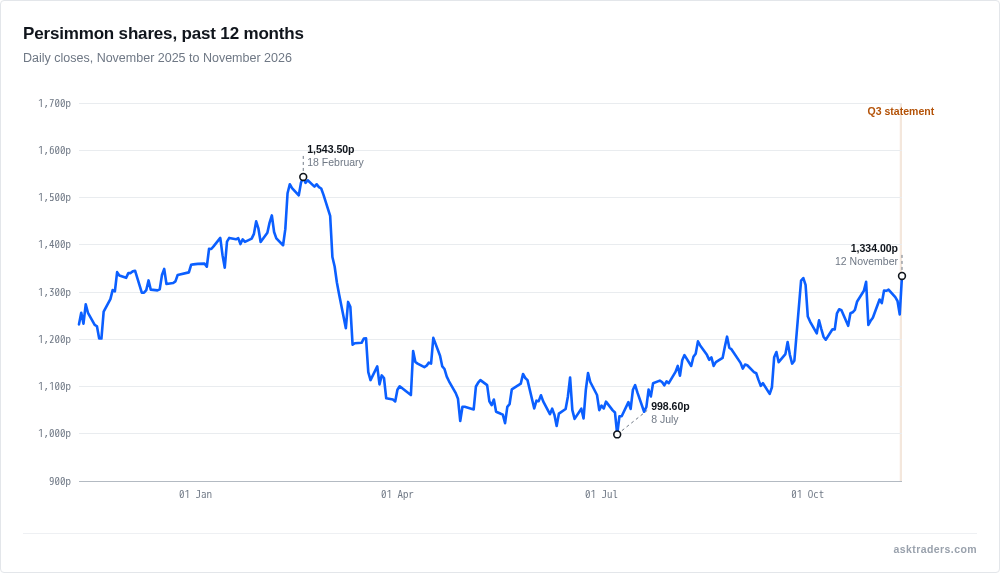
The shares stood at 1,327.75p at 11.42am today, up 6.0% from yesterday’s close of 1,252.5p, after trading between 1,283p and 1,331.5p. That is about 7.7% above a year ago, but below the 1,543.5p closing high in February.
PSN.LSE
The statement, published at 7am and covering 1 July to 1 November, was headlined “Market share gains and planning success support full-year growth”. Dean Finch, Group Chief Executive, said:
Sponsored content
Ready to put what you’ve learned into practice?
Try IG’s platform with £10,000 in virtual funds and practise trading
without putting your own money at risk.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Learn the markets with IG Academy
Build your knowledge with IG Academy educational content, then use a
demo account to practise what you’ve learned on the IG platform.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
See how trading works before risking real money
IG’s demo gives you access to thousands of markets and £10,000 in
virtual funds, so you can explore the platform and test your ideas first.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Turn trading theory into practical experience
Learn with IG Academy, explore charts and market tools, and practise
strategies in a simulated trading environment before going live.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Ready to take your learning further?
IG combines market education, analysis and an established trading platform,
giving you the tools to keep learning as you develop your trading skills.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Our clear strategy has allowed the Group to increase both sales and planning approvals at a time when the overall sector is declining.
Dean Finch, Group Chief Executive, Persimmon
The evidence is a better sales rate, meaning homes sold per site per week, and a firmer order book, the homes already sold but not yet completed. Planning approvals, final permission to start building, rose 12% to 8,722 plots in the nine months to 30 September.
Measure
This year
Last year
Net private sales rate
0.79
0.76
Rate excluding bulk deals
0.65
0.63
Total forward sales
£2.82bn
£2.79bn
Private average price in order book
c.£301,900
c.£295,150
Average sales outlets
263
272
Sales improved even though Persimmon averaged 3% fewer active building sites, so each site sold more.
Persimmon’s share price over the past 12 months, with today’s jump after the Q3 trading statement.
Three brokers rate the shares a Buy, according to Proactive Investors. Panmure Liberum has a 1,694p target and credits product, pricing and execution. Jefferies, at 1,590p, points to land pipeline growth and more than 100 outlet openings planned for 2027. Peel Hunt’s target is 1,420p.
Sponsored
The caveat is 2027. Persimmon expects inflation to add c.£30m-£40m of costs, which with higher financing costs it says will limit near-term profit progression. Peel Hunt expects a cut of less than 2% to consensus 2027 pre-tax profit. The next update, for the full year, is due on 12 January 2027.
The AskTraders Analyst Team features experts in technical and fundamental analysis, as well as traders specializing in stocks, forex, and cryptocurrency.
Stay ahead of the markets
Sign up to our free Morning Markets email, every weekday before the open.
Stay ahead of the markets
Morning Markets
Weekdays
FTSE, overnight moves and what matters before the open.
Show personalised advertising and content, and measure how adverts and content perform
Learn about our audience and develop and improve our services
Learn more
Advertising pays for our free market news, analysis and trading tools.
If you accept, we and our partners may also match and combine data from other sources, link your devices, and identify your device from its characteristics, precise location or by actively scanning it. Some partners rely on legitimate interest rather than consent for certain purposes; you can object in the full list.
You can reject, or choose which purposes to allow under Manage options. Your choice is kept for this browser and you can change it at any time. See every purpose and partner
Necessary
Always active
Needed to run AskTraders and to remember your choice here. Always on.
Preferences
Remembers choices you make on AskTraders, such as display settings.
Analytics
Lets us count visits and see which pages are useful, using tools such as Google Analytics.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Advertising and personalisation
Lets us and our advertising partners show personalised adverts and content, measure them and learn about our audience, and lets us offer web push notifications. See every purpose and partner
We and our advertising partners use cookies to show relevant advertising and measure its performance. You can opt out of the sale or sharing of your personal information, and of personalised advertising, at any time using the link below.
Necessary
Always active
Needed to run AskTraders and to remember your choice here. Always on.
Preferences
Remembers choices you make on AskTraders, such as display settings.
Analytics
Lets us count visits and see which pages are useful, using tools such as Google Analytics.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Advertising and personalisation
Lets us and our advertising partners show personalised adverts and content, measure them and learn about our audience, and lets us offer web push notifications. See every purpose and partner