
Western Digital (NASDAQ: WDC), the hard disk drive maker, reported quarterly revenue of $4.381bn and non-GAAP earnings of $4.64 a share, both above forecasts, and the shares rose 2.1% in post-market trading. The results arrived after the US close, so they played no part in the day’s fall.
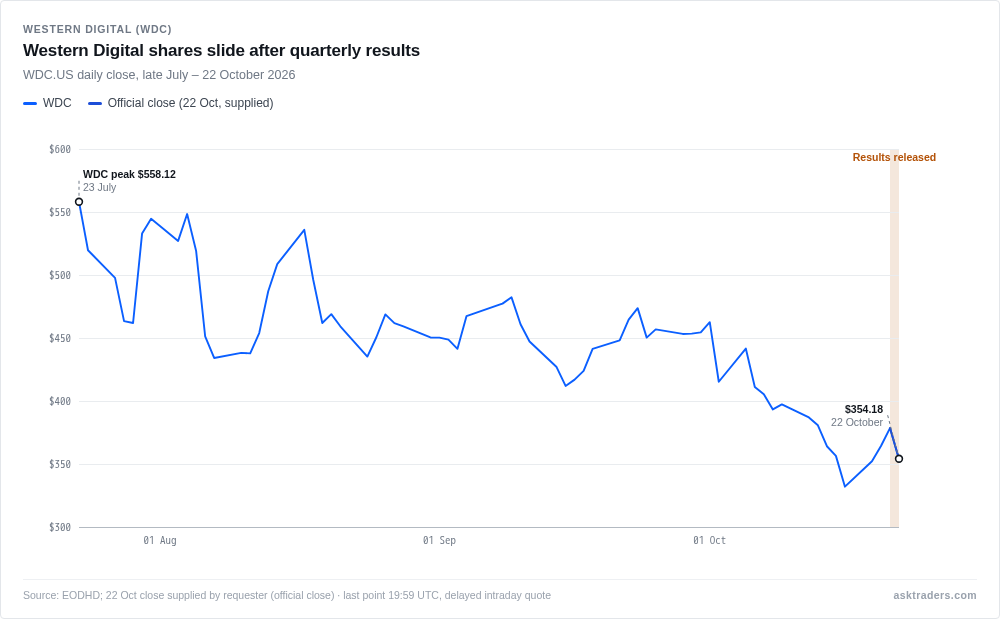
The stock closed the regular session at $354.18, down 6.4%, as the Nasdaq Composite fell 2.6%. Yahoo Finance headlines described Big Tech leading the AI trade lower and a $2.7T chip sell-off. The shares had already slid from above $500 in late July.
Revenue rose 55% from $2.818bn a year earlier. Non-GAAP gross margin, which strips out certain items, was 58.1% against 43.9% a year ago. Chief executive Irving Tan said:
Fiscal 2027 is off to a strong start, with results exceeding expectations, driven by robust customer demand and disciplined execution.
Irving Tan, CEO, Western Digital
Guidance, the company’s own forecast, matters more. Western Digital expects second-quarter revenue of $5.1bn, plus or minus $100m, and non-GAAP earnings of $5.80 a share, plus or minus $0.20. Consensus, the average of analysts’ forecasts, was $4.57bn and $4.82 on Yahoo Finance, before the guidance was issued.
| Metric | Reported | Yahoo consensus | Difference |
|---|---|---|---|
| Q1 revenue | $4.381bn | $4.15bn | +5.6% |
| Q1 non-GAAP EPS | $4.64 | $4.10 | +13.2% |
| Q2 revenue | $5.1bn guide midpoint | $4.57bn | +11.6% |
| Q2 non-GAAP EPS | $5.80 guide midpoint | $4.82 | +20.3% |
The guidance midpoints sit well clear of consensus, though they are forecasts rather than results. The company also raised its dividend 17% to $0.175 a share, payable on the 17th of December to holders of record on the 4th of December, and bought back $1.001bn of shares in the quarter.
Wedbush, the US broker, rates the stock Outperform; in a note on 21 October its analyst Matt Bryson wrote that hard disk drive vendors “again almost certainly set beatable bars”. Chief financial officer Kris Sennesael pointed to exabyte growth and improved pricing behind the quarter.
The release flags revenue concentration in the Cloud end market and among top customers as a risk. Seagate, the main rival in hard drives, reports next Tuesday, according to Seeking Alpha.