
HE1, or Helium One is a relatively young company, founded in 2015 and listed in December 2020 on AIM on the London Stock Exchange under ticker LON: HE1.
The HE1 share price has had a rapid ascent through 2024, adding more than 440%, and drawing plenty of attention, but we would be remiss if we didn’t mention the market cap of the firm playing a part. At a shade over £70million, it takes significantly less weight for the market to move with such volatility than it would for a bigger firm. That is not to say that gains should be discounted as due to size alone, but taking a look at the longer term chart, and the prevailing 12 months gives us a different result entirely.
Whilst recent momentum is very much with Helium One shares, over the past 12 months the price has dipped by more than 80%. This kind of volatility will appeal hugely to some, but be the opposite of what others are looking for.
Latest HE1 News
In a short space of time after its IPO in 2020, Helium One Global shares jumped before a significant decline. Investors often display a tendency for being early adopters and pounced upon this stock in a big way. ‘Piling on’ may be a better description, but hype in the stock market can drive share values beyond reason in a flash, only to plummet when reality sets in.
Some analysts refer to this type of price action as a ‘tortoise shell’ formation. You want to be on the front end, not the latter. HE1 shares have not given holders much to smile over the past 12 months, and you will see from the 52 week range above that the stock is trading much closer to 52 week lows than highs. All investors would love to be able to buy a stock ‘at the bottom’, but trying to time the market perfectly can be a fools game.
In the case of pennystocks, as this one finds itself, you have to know first and foremost that the risk is significantly higher to that you will encounter with blue chips, and prudent risk management would reason that if you are to consider these types of companies as additions to your portfolio, the level of exposure be kept to small percentages.
Operationally, there have been developments that have led to this shift earlier in 2024, as you can see below.
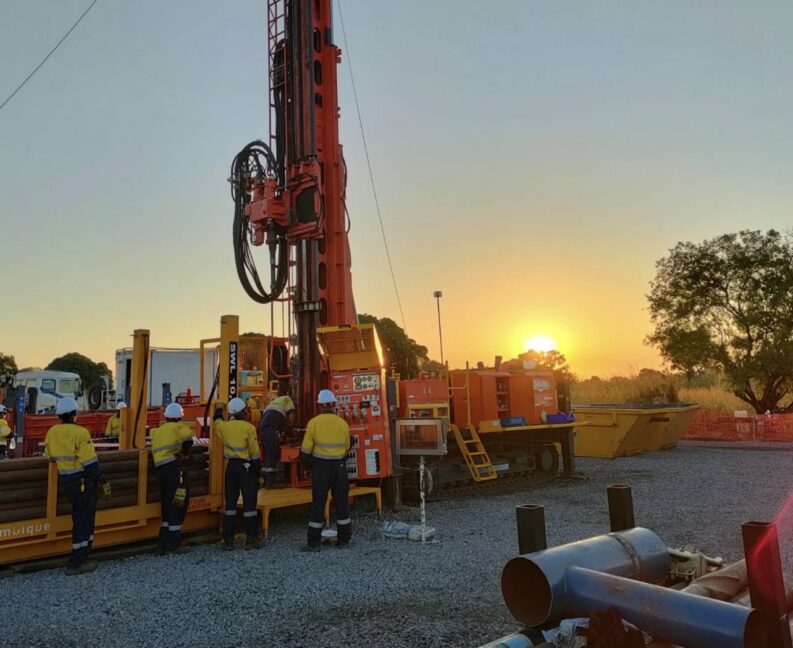
A huge upshift in momentum also occurred in late January, when it was announced that the Itumbulu West-1 Well had successfully reached TD. As the flow to surface was confirmed in Feb, the sentiment was clearly bullish for a period. The well successfully flowed a high concentration of helium to surface from Basement, at a measured concentration up to 4.7% helium (almost nine thousand times above background levels).
From the interim unaudited half year results being issued on March 7, the stock price has again shifted back into a period of sideways trading, after an initial drop of more than 25%. Here is a link to the report.
Who Is Helium One Global Ltd?
The firm’s focus is on the helium commodity market. Its plan is to become a major producer of this non-renewable commodity for the world market, where it is used in modern technologies that range from the medical sector to all manner of high-tech solutions.
HE1 is supposedly sitting on not one but three valuable Helium fields. Helium is a necessary ingredient in a variety of manufacturing processes, most of which are new-age and complex technologies.
Although helium is the second most abundant element in the universe next to hydrogen, its accessible supplies around the world are diminishing at a rapid rate. Tech giants such as Amazon, Alphabet, Facebook and several others, in addition to those in the medical field, depend heavily upon this noble gas. Forbes has been quoted as saying: “Helium is soaring on red-hot-demand, shrinking supply” (source: Forbes).
Helium One was conceived to tap into this critical shortage in the market and is led by new CEO Lorna Blaisse after the departure of former chief executive David Minchin. Blaisse was previously the Principal Geologist at Helium One and has over 17 years of experience in the exploration and appraisal of oil and gas projects across Africa.
With minimal financing, HE1 has acquired exclusive licensing rights to develop nearly 5,000 square kilometres of supposedly helium-rich deposits at three separate locations in Tanzania. Helium One has focused on its primary property, Rukwa, while testing has proceeded on its second site, Eyasi, with minimum attention paid to its third location, Balangida. Sufficient infrastructure is near each of these sites, and each one is within 130 to 800 kilometres of a major city or port.
Is Helium One worthy of your consideration at this time? Analysts are cautious, as you might expect after the stock’s rollercoaster ride, but for small drilling firms such as Helium One, any positive headlines in the press can drive the price through the roof in short order. More negative news will only harden resistance.
Where Will Helium One’s Stock Price Be In 12 Months?
Due to the speculative nature of Helium One at this stage in its development, a projection of share prices at this moment would be a pure guess. Helium One is an early-stage company still developing its business. Yes, helium prices are expected to rise significantly over the coming years, but this company will not be producing products for sale anytime soon.
There is no significant drilling history to fall back upon, just a few test drills to determine potential. The question remains as to whether these sites are commercially viable.
The concern is mainly the company’s cash burn rate. Helium One stated in March this year that it successfully raised £9.9 million in December 2022 to fund the company through the 2023 Drilling programme in the Rukwa Basin, anticipated in the third quarter of 2023.
Helium One Long-Term Forecast
What is the Helium One Global stock forecast for 2027? The current stock price could always be multiples higher, or shares of Helium One could crumble in the near and long run. The market is demanding solid evidence that the Tanzanian fields can yield high-grade helium as promised before leapfrogging this short-term value.
Even if major finds are confirmed, the firm will require a good amount of additional capital to deliver its product to the marketplace. The company has already noted that a processing plant will require $50m to get off the ground and produce 3.5m cubic feet of helium annually.
The current estimate for the Rukwa project alone is for a potential of 138bn cf. With operating costs of $6m and revenues approaching $100m, a very profitable business plan could be a real possibility for this company.
If positive finds are confirmed, HE1 may never have to raise additional capital. In situations such as these, the preferred exit strategy is for a major mining concern to take an interest and propose a takeover price that will satisfy long-term investors. Investors may not achieve the highest potential for their holdings, but an early payoff frees up capital for other investments rather than tying up the funds for more speculation, additional capital raises, and more performance risk.
Is Helium One a Good Buy
Is Helium One a good stock to buy for the long term? HE1 is speculative investing at its best and worst if it fails.
So the question is, is Helium One Global Ltd a buy or a sell? Caution is the byword here unless you are an investor who likes to take highly risky bets with very large payoff potential. Investors want more confirmation of profitable helium deposits before driving up this stock price any further, for the near or long term.