
Nostrum Oil & Gas (LON: NOG) completed the US$304.6m sale of its Kazakhstan operations to Altaris Holding Ltd. yesterday, the company announced at 7am today. The London-listed group has sold its operating subsidiaries and now moves to a managed wind-down.
The shares fell from 4.0p on the 14th of August, the last session before the deal was announced, to 0.75p by the 20th of August. The 52-week range is 0.5p to 4.5p.
Altaris, an Astana-based vehicle owned 51% by Alturion Holding Limited and 49% by Fincraft Energy Holding Limited, bought Zhaikmunai LLP, which holds the Chinarevskoye field licence, and POSITIV Invest LLP, which holds the Stepnoy Leopard fields. The proceeds redeemed the senior secured notes, bonds backed by claims on assets, in full, including accrued and default interest.
Nostrum will also buy back US$417.5m of its senior unsecured notes, bonds with no asset backing, leaving US$100m outstanding. Those carry no interest and mature on the 31st of December 2028. The cash price for the buyback will be announced in the coming days.
Chief Executive Officer Viktor Gladun described the deal as a conclusion to a long sales effort.
For Nostrum, the transaction represents the successful conclusion of a lengthy strategic sale process, enabling the Group to redeem its Senior Secured Notes in full and substantially reduce its remaining indebtedness.
Viktor Gladun, Chief Executive Officer, Nostrum Oil & Gas
The group keeps its unrestricted cash, while US$10m of the price sits in escrow, money held with a third party, for at least six months against warranty claims. The price can still change after completion. The notes had matured on the 30th of June and the group could not repay them then.
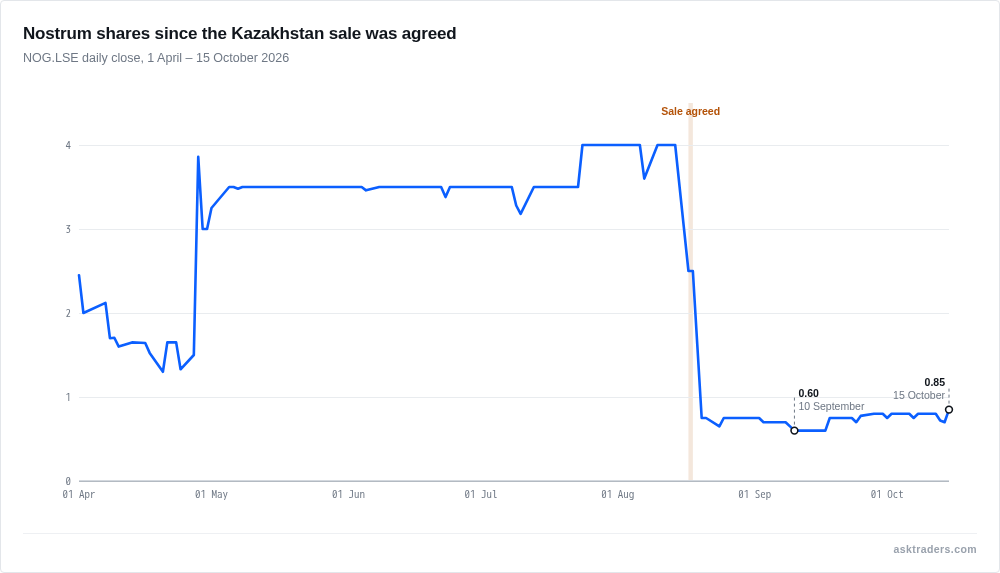
Completion removes the risk that the sale fails, but not the risk to equity. In its announcement of the 17th of August, the company said it did not currently expect residual proceeds for ordinary shareholders to be material, if any, though it did not rule out a final distribution at the end of the wind-down. The share price fall is consistent with that statement.
Shareholders rank behind the remaining US$100m of unsecured notes and the costs of winding down. The market value is about £1.4m on 164.95m shares, so any return to shareholders depends on a final distribution the company has not ruled out.