

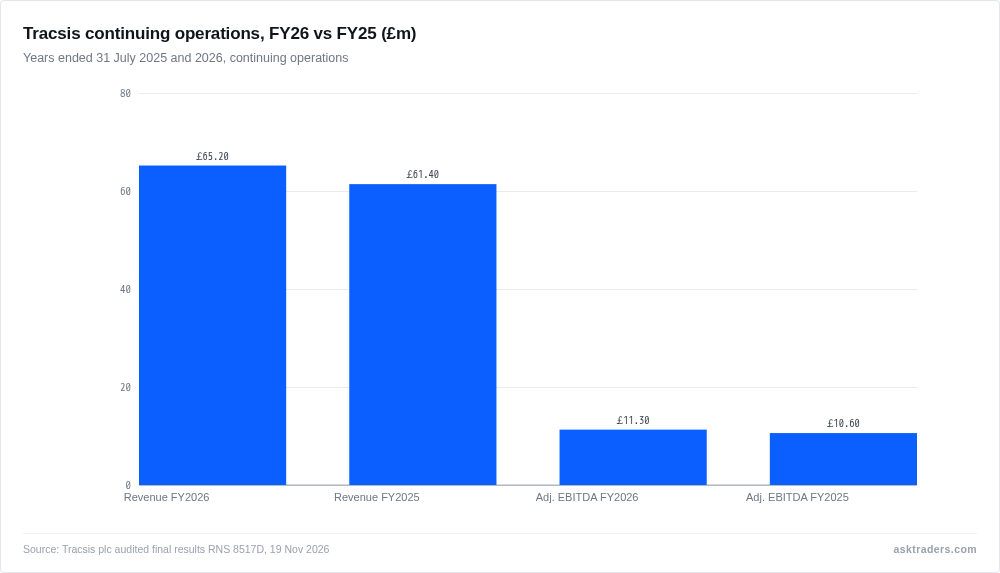
Tracsis (LON: TRCS) reported a 6% rise in continuing revenue to £65.2m for the year to the 31st of July, alongside a statutory pre-tax loss of £1.0m. The rail and transport technology group published its audited results at 7am today.
Adjusted EBITDA, a company-defined measure of profit before interest, tax, depreciation, one-offs and share-based pay, also rose 6% to £11.3m. Adjusted diluted earnings per share climbed 10% to 23.4p, and recurring licence and transactional revenue grew 10%.
The loss came from £4.5m of exceptional costs, one-offs stripped out of adjusted profit: £1.3m for the One Tracsis restructuring and £3.2m of third-party fees on acquisitions. The statutory loss per share from continuing operations was 5.1p, against a 0.2p loss a year earlier.
Cash was weaker. Free cash flow and year-end cash both fell, and the pre-tax result swung from a profit.
| Metric | FY2026 | FY2025 |
|---|---|---|
| Revenue (continuing) | £65.2m | £61.4m |
| Adjusted EBITDA (continuing) | £11.3m | £10.6m |
| (Loss)/profit before tax | £(1.0)m | £0.8m |
| Free cash flow | £3.0m | £7.7m |
| Cash | £19.4m | £23.4m |
Free cash flow fell to £3.0m from £7.7m, and cash to £19.4m from £23.4m, even as revenue and adjusted EBITDA rose.
The group also reshaped itself. It bought German ticketing provider Vesputi on the 31st of March, sold its Events business on the 31st of July, and bought Mistral Data, a cloud-based rail software firm, on the 23rd of August for a £48m enterprise value.
Mistral was funded from cash and a revolving credit facility (a flexible bank borrowing line) from HSBC UK Bank, extended to £40m, of which £38.7m was drawn. Pro forma, recurring licence revenue rises from 27% to about 45% of revenue, and adjusted EBITDA margin from 15.8% to about 20%.
Chief Executive Officer David Frost said the changes sharpen the focus of the business.
These strategic developments concentrate the Group on transport software, improve our revenue quality and profitability, and give us a more scalable business.
David Frost, Chief Executive Officer, Tracsis
The board is confident of FY27 adjusted EBITDA of at least £15.5m, which it calls in line with market expectations. The mean of four analysts’ forecasts compiled by the company is £15.4m. An investor presentation is due tomorrow at 1pm.
Pro forma net debt is about 1.5 times adjusted EBITDA after Mistral and is expected to fall to about 1.0 times by the end of calendar 2027. UK rail funding and procurement timelines remain uncertain, the company said.