
Taylor Wimpey shares (LON:TW.) are a component of the FTSE 100, as well as being included in the FTSE All-Share, FTSE 350 High Yield, and FTSE 350 indices.
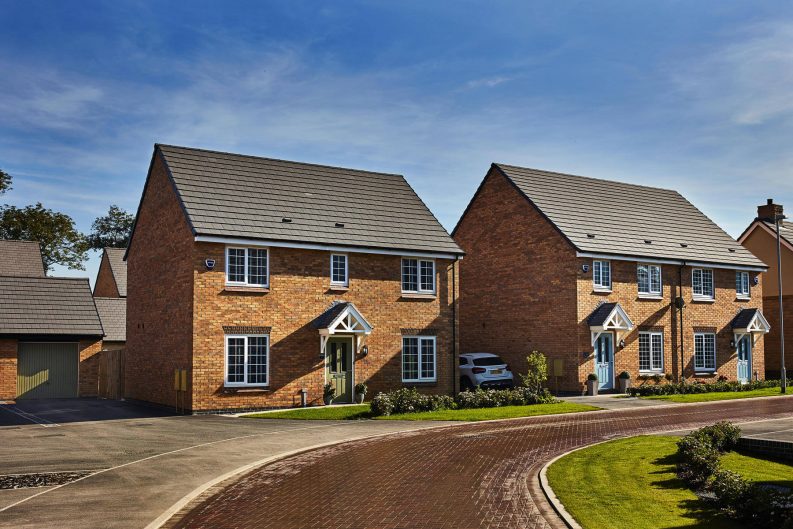
The company are a stalwart of the UK homebuilding sector, known for its extensive portfolio of residential developments across the United Kingdom.
While some analysts are projecting a strong rebound driven by pent-up demand and easing mortgage rates, the company’s recent performance and the broader economic climate warrant a more cautious assessment.
Adding another layer of complexity is the ongoing investigation by the Competition and Markets Authority (CMA). Taylor Wimpey is among several UK housebuilders under scrutiny for suspected breaches of competition law, including the sharing of commercially sensitive information. The extension of this investigation, with an expected conclusion by August 2025, introduces an element of uncertainty that could weigh on investor sentiment.
Taylor Wimpey Share Price Forecast
Despite operational challenges, some analysts maintain a bullish outlook. CitiGroup analysts, for instance, have highlighted Taylor Wimpey and Bellway as top picks, anticipating a strong rebound in the housing market due to declining mortgage rates and pent-up demand.
The expectation is that as mortgage rates become more affordable, potential homebuyers who have been sidelined will re-enter the market, driving demand for new homes. This scenario hinges on the assumption that the UK economy will stabilize and that consumer confidence will improve.
Jefferies Financial Group reaffirmed its “buy” rating on March 3, 2025, with a price target of GBX 175, suggesting a substantial potential upside. Similarly, Berenberg Bank reiterated its “buy” rating on May 2, 2025, setting a price target of GBX 150. These endorsements reflect an underlying belief in Taylor Wimpey’s long-term prospects and its ability to capitalize on a future market recovery.
The Flip-Side : Bulls Vs Bears
While the prospect of declining mortgage rates is undoubtedly positive, it is not a guaranteed panacea for the housing market’s woes. Several factors could undermine a potential recovery.
Firstly, even with lower mortgage rates, affordability remains a significant concern for many prospective homebuyers, particularly in regions with high property prices. Secondly, the UK economy is still grappling with inflationary pressures and the lingering effects of recent economic shocks. A further economic downturn or a resurgence of inflation could derail any potential housing market rebound. Thirdly, the supply of new homes may not be sufficient to meet the pent-up demand, leading to price increases that could once again deter potential buyers.
Finally, the long-term impact of Brexit on the UK housing market is still uncertain, and any adverse developments could further dampen demand. It is also worth pointing out that even if demand does pick up, there is no guarantee that Taylor Wimpey will be a primary beneficiary, given the highly competitive nature of the housebuilding industry.
Bull Case Summary:
- Declining mortgage rates will stimulate housing demand.
- Pent-up demand from sidelined homebuyers will drive sales.
- Analyst “buy” ratings indicate confidence in long-term prospects.
- Taylor Wimpey’s strong brand and extensive land bank position it well for future growth.
Bear Case Summary:
- Rising construction costs could erode profit margins.
- Ongoing CMA investigation creates uncertainty.
- Economic headwinds and inflationary pressures could dampen housing demand.
- Historical share price decline raises concerns about long-term profitability.
While analyst optimism and the prospect of a housing market rebound offer potential upside, the company must navigate a range of challenges, including rising costs, regulatory scrutiny, and macroeconomic headwinds. A balanced and realistic assessment of the risks and opportunities is essential for investors considering Taylor Wimpey as part of their portfolio. The contrarian view suggests that relying solely on the narrative of declining mortgage rates and pent-up demand may be overly simplistic, and a more cautious approach is warranted.
Latest Operational Developments
Taylor Wimpey’s core business revolves around the acquisition of land, obtaining planning permissions, and constructing and selling residential properties. With a significant presence in various regions of the UK, the company caters to a diverse range of homebuyers, from first-time buyers to families seeking larger homes. Its operational success is intrinsically linked to the health of the UK housing market, making it particularly sensitive to fluctuations in interest rates, consumer confidence, and government policies. The recent cautionary note regarding rising construction costs, attributed to suppliers mitigating the impact of budget tax changes and uncertain economic conditions, is a clear indicator of the challenges the company faces in maintaining profitability.
The company’s 2024 financial results reveal a nuanced situation. While Taylor Wimpey completed the sale of 9,972 homes, this represents a slight decrease from the 10,356 homes sold in 2023. Furthermore, the average selling price for privately sold homes dipped from £370,000 in 2023 to £356,000 in 2024.
This decline in both volume and average selling price suggests that Taylor Wimpey is not immune to the pressures facing the broader housing market. The anticipation of full-year operating profit aligning with previous forecasts of £416 million offers some reassurance, but it’s essential to consider the factors that could potentially impact future performance.