
This is a US-led week for UK traders, with no central bank rate decision and no UK inflation or labour-market release scheduled. The main test is US consumer price inflation on Wednesday, followed by US retail sales on Thursday. Tuesday brings the first big US bank results of the earnings season. A surprise in the US figures would move US rate expectations, sterling against the dollar and US shares, while the UK’s August GDP and production data on Thursday sit a rung below.
Where markets and rates stand
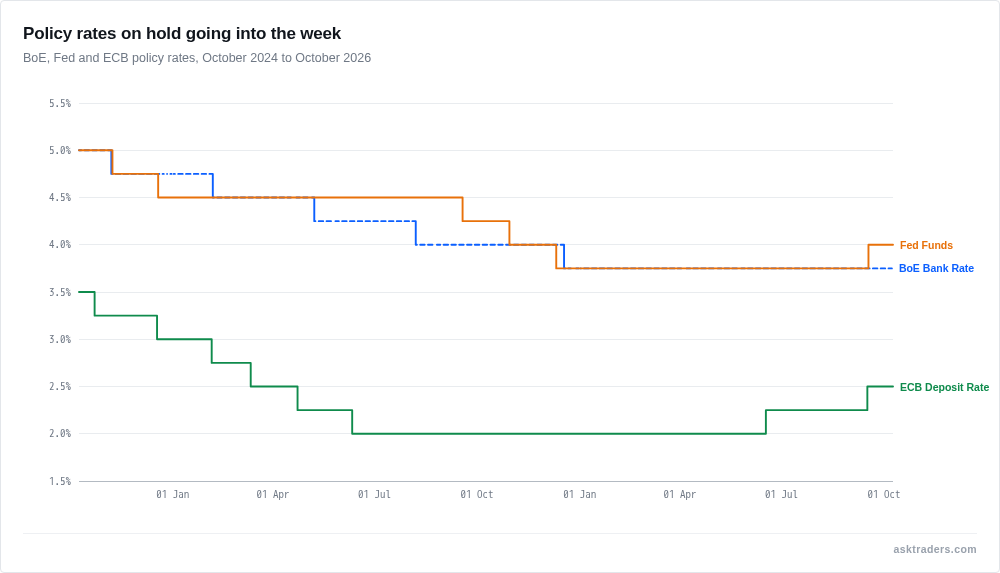
The Bank of England’s Bank Rate is 3.75%, the Fed’s target range is 3.75% to 4.00% and the European Central Bank (ECB) deposit rate is 2.5%. No decision from any of the three is scheduled this week.
The S&P 500 closed on Friday at 7,811.54, up 0.59% on the day, and GBP/USD ended Friday at 1.32286.
Monday
No scheduled releases from our watchlist. Several Bank of England policymakers are due to speak.
Tuesday
- Before the US open, US: earnings from JPM, GS, C, WFC, JNJ and UNH.
- 11:00 UK: US existing home sales, September, month on month. Consensus -0.3%, previous -2%.
Wednesday
- Before the US open: earnings from BAC, MS and ASML.
- 13:30 UK: US consumer price index (CPI), the cost of living, September. Consensus 3.6% year on year, previous 3.4%; 0.6% month on month, previous 0.4%.
- 13:30 UK: US core CPI, which excludes food and energy. Consensus 2.5% year on year, previous 2.4%; 0.2% month on month, previous 0.3%.
Bank of England speakers including Bailey and Pill are also due.
Thursday
- 07:00 UK: GDP, August, month on month. Consensus -0.1%, previous 0.4%.
- 07:00 UK: industrial production, August, month on month. Consensus -0.1%, previous 0.2%.
- 13:30 UK: US retail sales, September, month on month. Consensus 0.2%.
- Before the US open: earnings from TSM.
Friday
- 10:00 UK: euro-area harmonised inflation (HICP, the euro area’s inflation measure), September, year on year. Consensus 2.2%, previous 2.2%.
- 14:15 UK: US industrial production, September, month on month. Consensus 0.3%.
The Bank of England’s Bailey is due to speak again.
The two that matter most
US CPI is the week’s largest entry. Consensus forecasts point to a hotter print: headline inflation at 3.6% against 3.4% previously, and core at 2.5% against 2.4%. A reading above those forecasts would be the surprise most likely to shift US rate expectations, with consequences for the dollar and for US shares. A softer reading would cut the other way.
Retail sales on Thursday are the follow-up test of the US consumer, with consensus at 0.2% for the month. The week’s bank earnings, from Tuesday, set the tone for US shares before either release.
Key events
| Day | Time (UK) | Event | Previous | Consensus forecast |
|---|---|---|---|---|
| Tue 13 Oct | Before US open | Earnings: JPM, GS, C, WFC, JNJ, UNH | n/a | EPS: JPM 5.94, GS 12.9, C 2.66, WFC 1.85, JNJ 2.53, UNH 4.12 |
| Tue 13 Oct | 11:00 | US existing home sales (Sep, m/m, %) | -2 | -0.3 |
| Wed 14 Oct | 13:30 | US CPI (Sep, y/y, %) | 3.4 | 3.6 |
| Wed 14 Oct | 13:30 | US CPI (Sep, m/m, %) | 0.4 | 0.6 |
| Wed 14 Oct | 13:30 | US core CPI (Sep, y/y, %) | 2.4 | 2.5 |
| Wed 14 Oct | 13:30 | US core CPI (Sep, m/m, %) | 0.3 | 0.2 |
| Wed 14 Oct | Before US open | Earnings: BAC, MS, ASML | n/a | EPS: BAC 1.11, MS 2.83, ASML 12.47 (EUR) |
| Thu 15 Oct | 07:00 | UK GDP (Aug, m/m, %) | 0.4 | -0.1 |
| Thu 15 Oct | 07:00 | UK industrial production (Aug, m/m, %) | 0.2 | -0.1 |
| Thu 15 Oct | 13:30 | US retail sales (Sep, m/m, %) | n/a | 0.2 |
| Thu 15 Oct | Before US open | Earnings: TSM | n/a | EPS: 4.45 (TWD) |
| Fri 16 Oct | 10:00 | Euro-area HICP (Sep, y/y, %) | 2.2 | 2.2 |
| Fri 16 Oct | 14:15 | US industrial production (Sep, m/m, %) | n/a | 0.3 |
The UK GDP and production forecasts both point to a small monthly fall after growth in the previous reading, which makes Thursday morning the week’s one UK-specific test.


