Bellway Guides Lower on FY27 Homes and Margin, but Shares Rise
Bellway guided to fewer homes and a thinner margin for FY27 after a year of higher completions and profit, yet its shares rose in early trading, with the housebuilder enlarging its buyback.
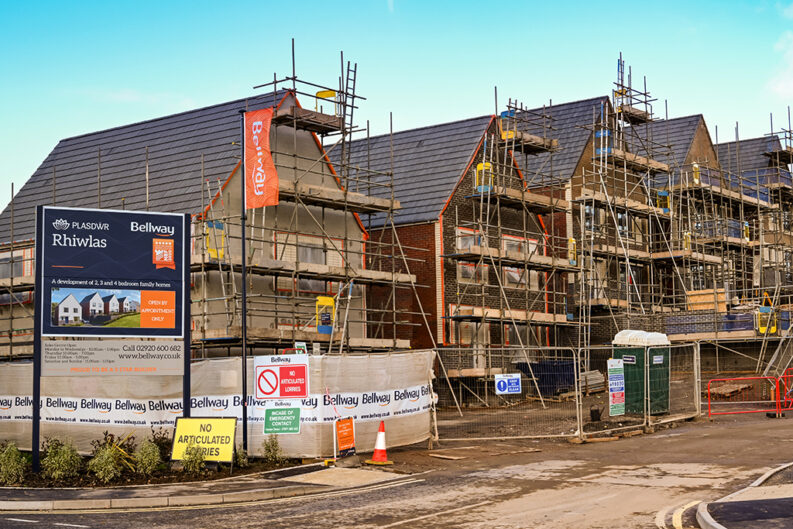
Bellway (LON: BWY), the UK housebuilder, reported higher completions and profit for the year to 31 July but guided to fewer homes and a lower margin in FY27. Its shares nonetheless rose in early trading today.
The stock was up about 2.7% at 2,039p by 9.08am London time, against 1,985p at yesterday’s close; the price is delayed and intraday. That is still about 29% below the 2,890p high of the 13th of February. The reason for the rise is not confirmed, but the bigger buyback and higher dividend possibly helped.
The full-year results, published at 7am, were solid against Bellway’s own prior year. Completions rose 10.8% to 9,695 homes, revenue 13.6% to £3,162.2m and underlying pre-tax profit 5.7% to £305.7m. Adjusted operating cashflow climbed 36.0% to £868.6m. Chief executive Jason Honeyman said:
Sponsored content
Ready to put what you’ve learned into practice?
Try IG’s platform with £10,000 in virtual funds and practise trading
without putting your own money at risk.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Learn the markets with IG Academy
Build your knowledge with IG Academy educational content, then use a
demo account to practise what you’ve learned on the IG platform.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
See how trading works before risking real money
IG’s demo gives you access to thousands of markets and £10,000 in
virtual funds, so you can explore the platform and test your ideas first.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Turn trading theory into practical experience
Learn with IG Academy, explore charts and market tools, and practise
strategies in a simulated trading environment before going live.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Ready to take your learning further?
IG combines market education, analysis and an established trading platform,
giving you the tools to keep learning as you develop your trading skills.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Bellway has delivered a robust performance, growing both volume output and profits despite ongoing challenges across the housing market.
Jason Honeyman, Bellway
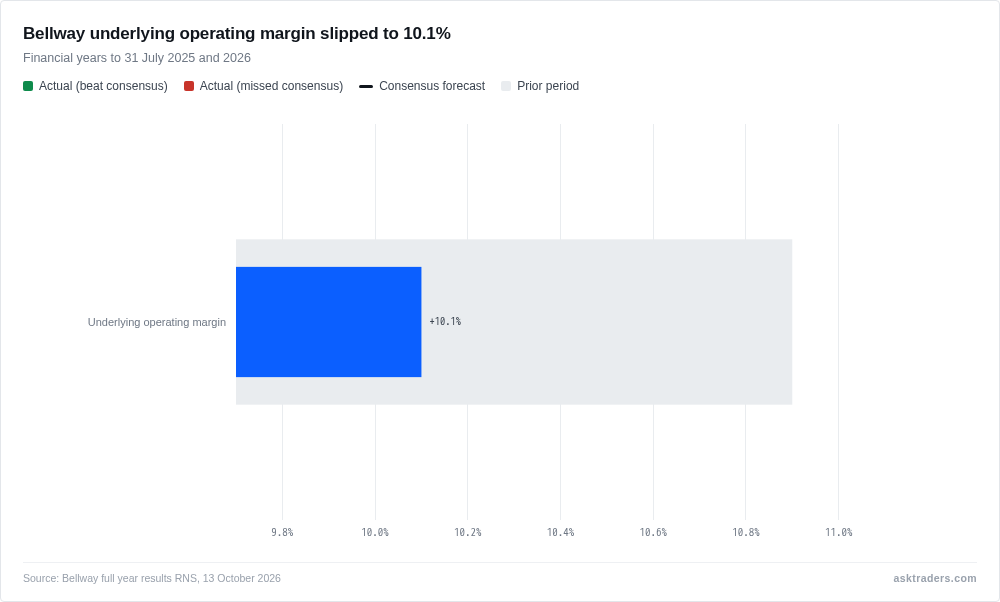
The squeeze sits in the margin and the outlook. Underlying operating margin slipped to 10.1% from 10.9%, and Bellway expects a further fall in FY27 from build cost inflation, elevated sales incentives and more bulk sale completions. It targets 9,000 to 9,400 completions, below this year’s 9,695.
Bellway’s underlying operating margin, financial years to 31 July. Source: Bellway.
Demand indicators back the caution. The order book stood at 4,981 homes against 5,285 a year earlier. The private reservation rate was 0.50 per outlet per week in the nine weeks since the 1st of August, against 0.51 a year earlier. Incentives averaged about 5%, up from 4.1%.
Shareholders get more cash. The dividend rises 7.1% to 75.0p, and the FY27 buyback is £150m, with the first tranche raised to £75m from £50m. Net cash ended the year at £157.7m.
Sponsored
Bellway said customer demand remains constrained by affordability pressures, with mortgage rates above prior-year levels. With the shares well below their February high, some of that caution may already be in the price; whether other housebuilders report the same weakness is the next test.
The AskTraders Analyst Team features experts in technical and fundamental analysis, as well as traders specializing in stocks, forex, and cryptocurrency.