Kier Group Wins Investment-Grade Rating From Fitch on Bond Repayment Plan
Fitch has lifted UK contractor Kier to investment grade, expecting its leverage to fall to zero by the end of the decade as it repays a £250m bond from cash. The shares were little changed.
Fitch Ratings has upgraded Kier Group (LON: KIE), the UK infrastructure services and construction contractor, to investment grade, moving it to ‘BBB-‘ from ‘BB+’ with a Stable Outlook. Kier announced the change this morning, although Fitch’s commentary is dated yesterday.
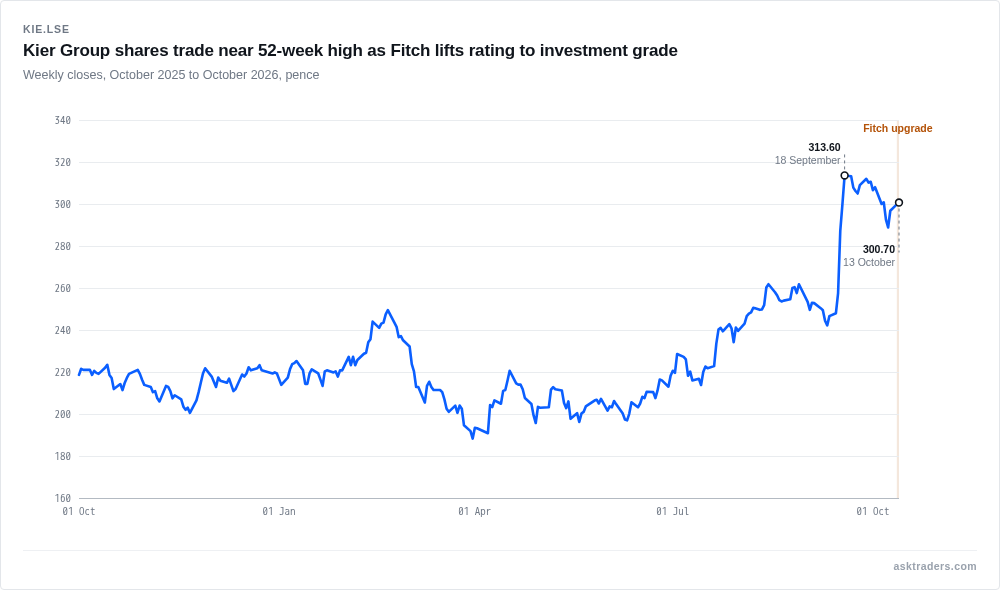
The shares traded at 300.70p in delayed quotes by late morning, up 0.3% on yesterday’s close of 299.8p. That is close to the 52-week high of 319.4p, reached in the week of the 28th of September, and about 37% above a year ago.
‘BBB-‘ is the lowest rung of investment grade. Kier said the decision highlights its growing balance sheet strength, strong cashflow and disciplined capital deployment. Fitch set out its own reasoning in its commentary.
Sponsored content
Ready to put what you’ve learned into practice?
Try IG’s platform with £10,000 in virtual funds and practise trading
without putting your own money at risk.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Learn the markets with IG Academy
Build your knowledge with IG Academy educational content, then use a
demo account to practise what you’ve learned on the IG platform.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
See how trading works before risking real money
IG’s demo gives you access to thousands of markets and £10,000 in
virtual funds, so you can explore the platform and test your ideas first.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Turn trading theory into practical experience
Learn with IG Academy, explore charts and market tools, and practise
strategies in a simulated trading environment before going live.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
Sponsored content
Ready to take your learning further?
IG combines market education, analysis and an established trading platform,
giving you the tools to keep learning as you develop your trading skills.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
“The upgrade reflects Fitch’s expectation that revenue growth and stable margins will reduce Fitch-defined EBITDA gross leverage to below the positive rating sensitivity and to zero by FY29-FY30 as Kier repays its GBP250 million bond under its updated strategy.”
Fitch Ratings
Leverage compares debt with EBITDA, a measure of operating profit before depreciation. Fitch forecasts 1.5x at the end of FY26 and 1.4x in FY27 and FY28, then zero, with positive free cash flow in each year from FY27 to FY30. Kier’s order book stands at £11.9bn, up from £11bn, and about 60% of it is cost-plus or target-cost work, where costs are passed through to the client.
Kier Group (KIE.L) weekly closes, Oct 2025–Oct 2026: shares near their 52-week high as Fitch upgrades the builder’s credit rating to investment grade.
The £250m senior unsecured bond falls due in February 2029, and Fitch expects it to be repaid from cash. Kier also has a £190m revolving credit facility, undrawn. Fitch expects lower finance costs from FY29, so the gain is credibility and flexibility rather than an immediate saving.
The muted reaction fits the run-up: the shares closed the week of the 14th of September at 313.6p, after results on the 15th, against 246.6p a week earlier. Fitch also says Kier is unlikely to be upgraded further, given its focus on one geographical region.
Sponsored
Fitch would consider a downgrade if leverage stays above 1.5x, or if the EBITDA margin sinks below 3.5% with neutral free cash flow.
The AskTraders Analyst Team features experts in technical and fundamental analysis, as well as traders specializing in stocks, forex, and cryptocurrency.